


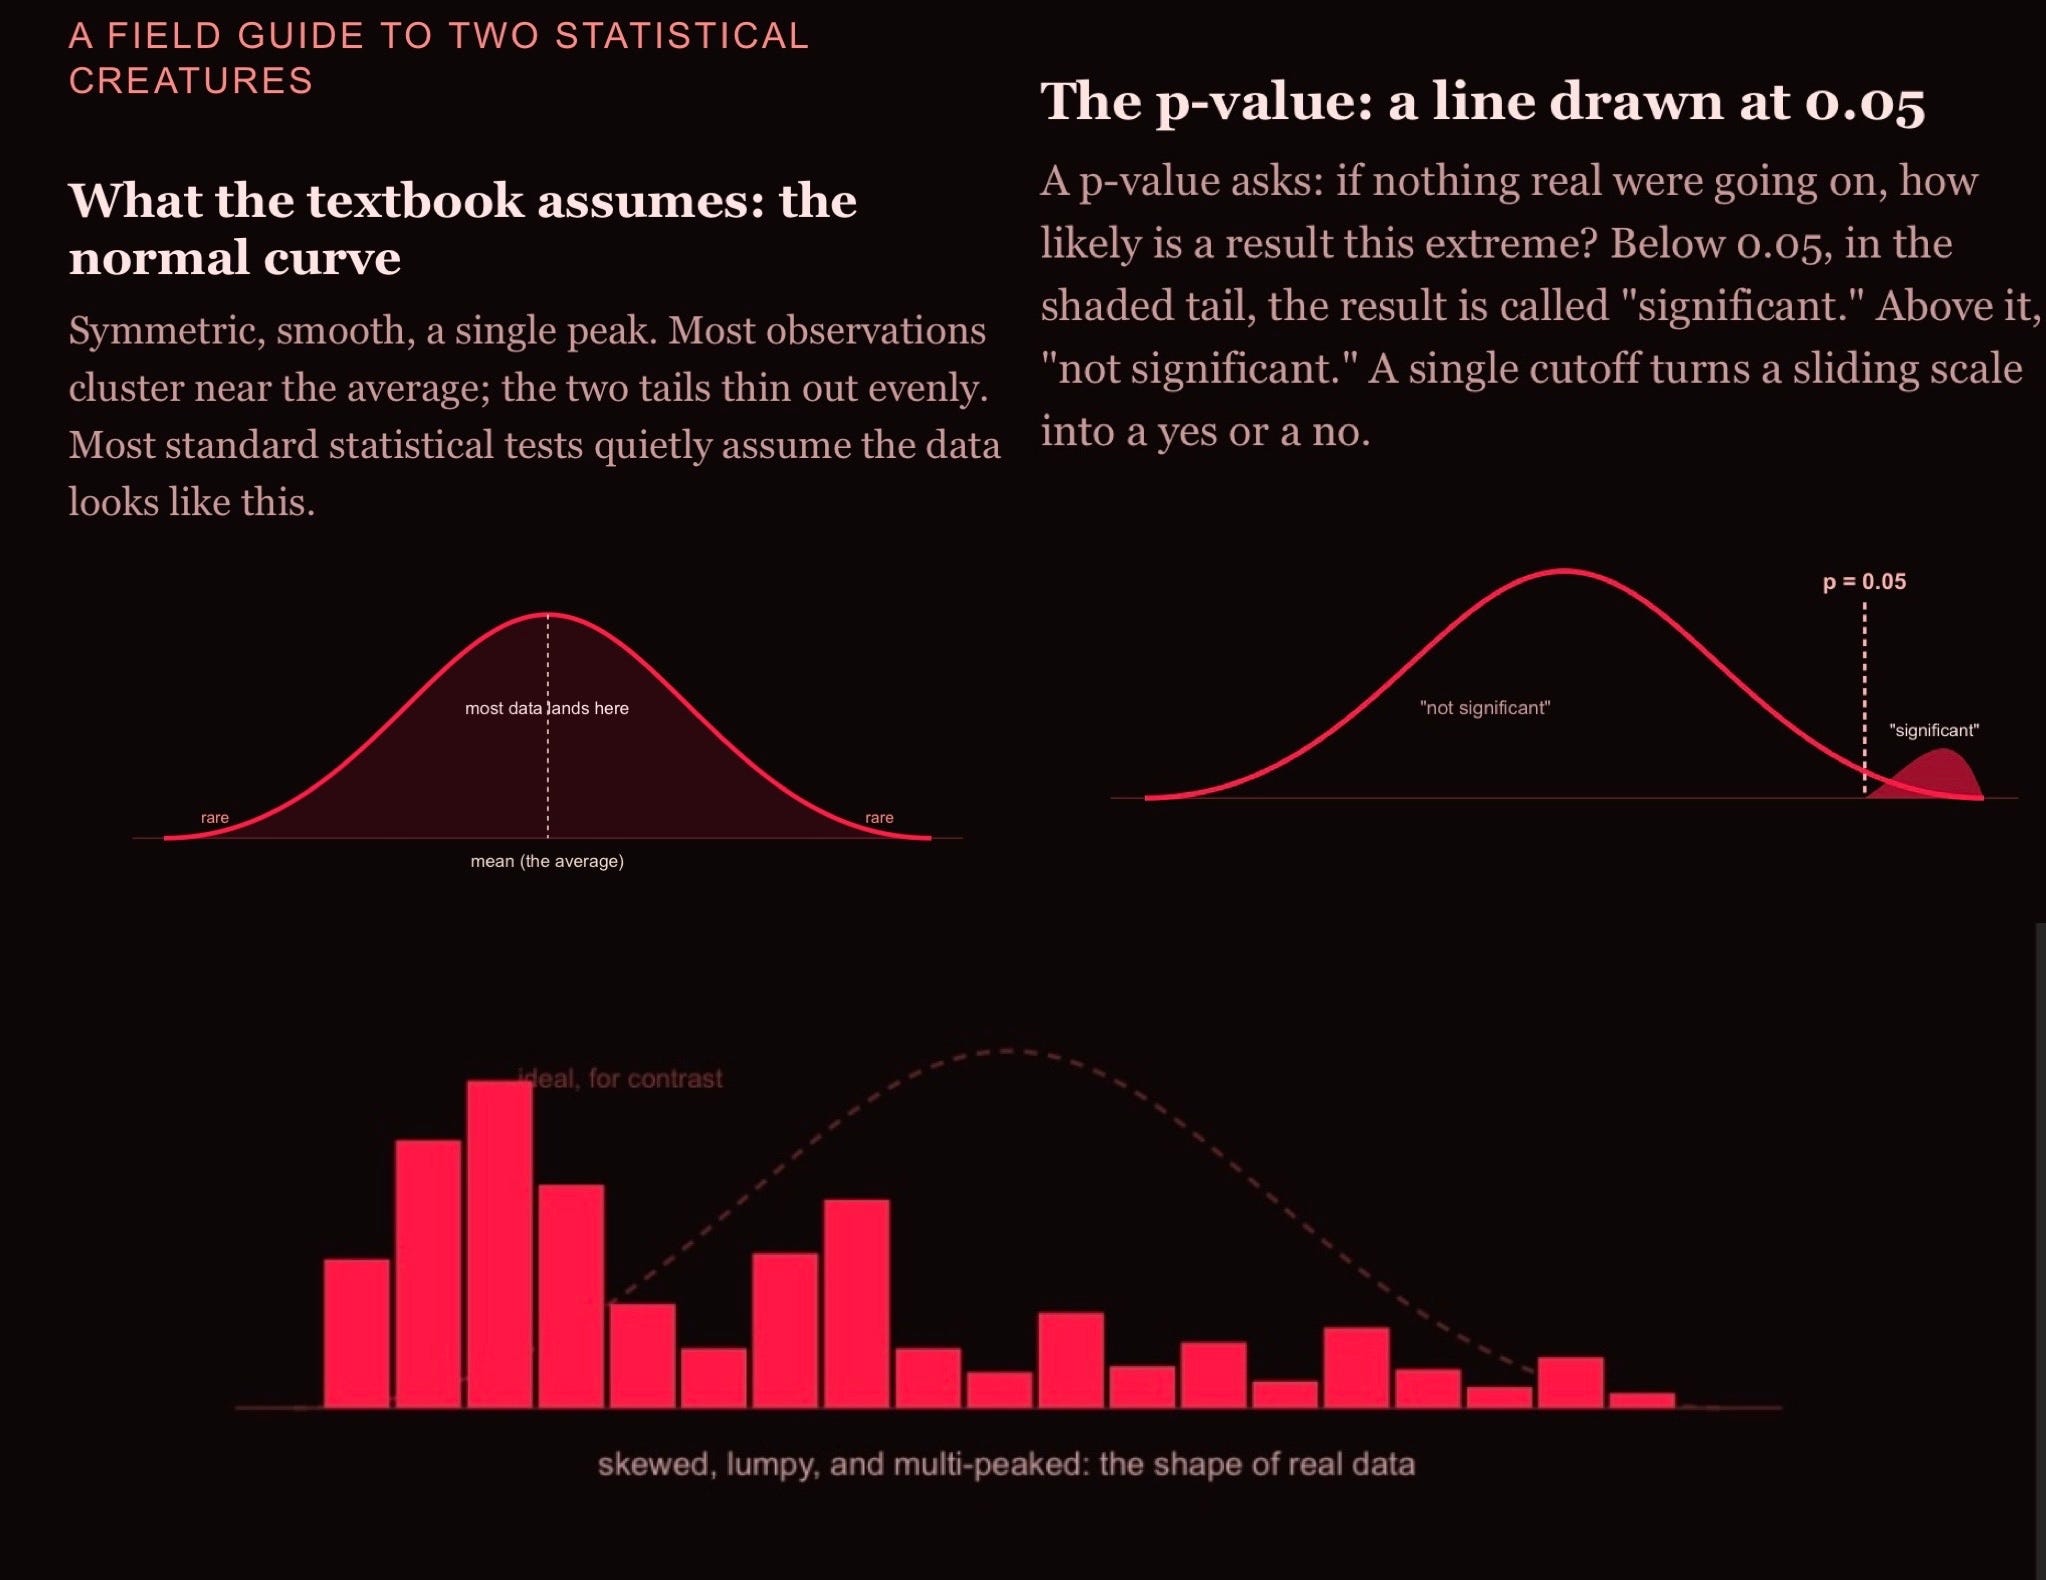
In 1989, statistician Theodore Micceri published a paper with one of the greatest titles in quantitative research: The Unicorn, the Normal Curve, and Other Improbable Creatures. The title was not a joke. Micceri examined 440 large-sample achievement and psychometric datasets and asked a simple question: how often did the normal distribution actually appear in practice?
The answer was zero.
Every one of the 440 distributions came back significantly nonnormal at the .01 level. Not one was statistically normal. Stretching the definition to its most generous, only 19 of them, 4.3 percent, even looked like reasonable approximations to the bell curve, and even those carried contaminations the eye missed.
The finding was awkward because the normal distribution occupied a central position in statistical practice. Researchers routinely assumed its existence when selecting methods, interpreting results, and drawing conclusions. Yet the creature itself appeared surprisingly rarely.
More than three decades later, Arjun Gupta revisited the metaphor in his Substack essay Unicorns, Gaussian Curves and Other Mythical Creatures (2022), arguing that researchers often continue relying on distributions that rarely appear in practice.
The p-value belongs in the same bestiary, because it provides the epistemological template for everything that follows. Micceri (1989) showed that the normal curve was assumed almost universally despite passing a formal normality test in none of the 440 datasets he examined. The p-value threshold of 0.05 functions as its horn: a single number that transforms a messy empirical reality into a legible binary. Significant or not significant.
These are all the same creature. The normal curve, the smooth distribution, the 0.05 cutoff: each is vanishingly rare in the wild, rare in the way the mythical unicorn is rare, something almost no one actually encounters, and each survives anyway, not because it is common but because it is useful. A shared convention lets large communities agree on what counts as evidence, so the belief holds even where the thing it describes almost never appears. That is precisely the logic of the unicorn
If statistics have their own unicorns, does finance? Now, you all finance people out there, who think you are the unicorn for inventing the word unicorn, think again. LOL
Venture capital developed its own in 2013, when Aileen Lee introduced the term “unicorn” for privately held startups valued at more than $1 billion. Like the p-value, the unicorn converts complexity into a category. Above the threshold or below it. Unicorn or not unicorn.
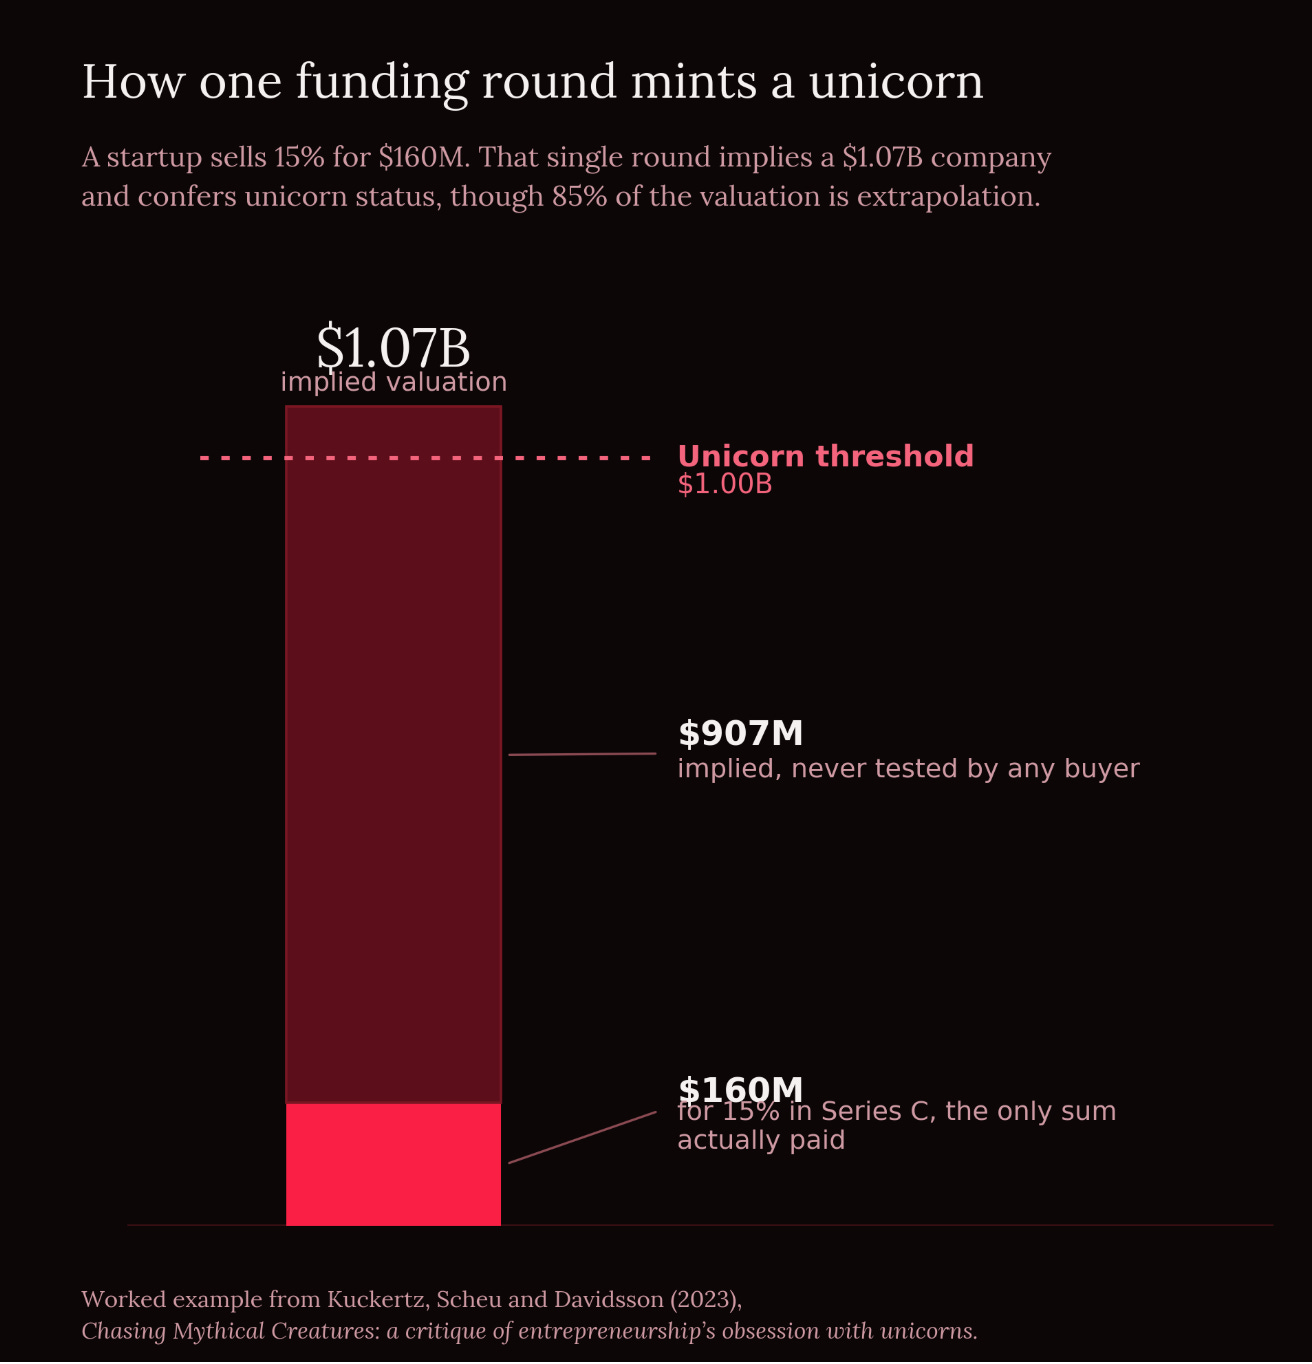
The comparison is not merely rhetorical. Kuckertz, Scheu, and Davidsson (2023) note that unicorn valuations are premarket valuations. Their own example is instructive. A startup raises $160 million for 15 percent of its shares in a Series C round. That single transaction implies a valuation above one billion dollars and confers unicorn status, even though no set of investors has shown willingness to pay that sum for the business as a whole. The largest amount any buyer actually committed was $160 million. The rest of the valuation is extrapolation. In both statistics and finance, a threshold transforms uncertainty into a conclusion.
Therefore, a unicorn, in a finance world, is a company whose valuation depends substantially on expectations about a future that has not yet arrived. This does not imply irrationality. Discounted cash flow models are poor instruments for transformative technologies, because terminal value dominates the calculation. For a mature firm, terminal value is already a substantial share of enterprise value. For an early-stage transformative company, it can be nearly the entire figure, which means the valuation rests almost wholly on assumptions about a discontinuous future that no model can pin down. Amazon traded at extraordinary multiples for more than a decade while being widely described as a bubble, and then became one of the most valuable companies in history. It was not a miscalculated cash-flow stock. It was a call option on the future of commerce, and venture and growth investors are in the business of pricing exactly that optionality.
Schwartz and Moon (2000) priced that option formally. Applying real-options techniques to Amazon at the close of 1999, their base case valued the stock at $12.42 against a market price of $76.125. The model could be made to match the market, but only by assuming a growth volatility that implied, on the authors' own reading, an unrealistic distribution of future revenues. A valuation that does not resolve to a conventional DCF is therefore not necessarily a fiction. It is a different instrument for a different type of asset. But the instrument still had to be priced off a distribution, and in 1999, the market was not pricing the models. It was pricing a more generous one that investors had collectively agreed to hold.
The argument here is narrower. The option may have value. Amazon, in the end, justified an extraordinary one. But a single favourable outcome does not retroactively make the optimistic distribution the correct one, any more than a winning ticket makes the wager wise. The question is whether a valuation reflects the actual probability distribution of outcomes or the distribution investors have agreed to believe in. Those are not the same question, and 1999 priced the second.
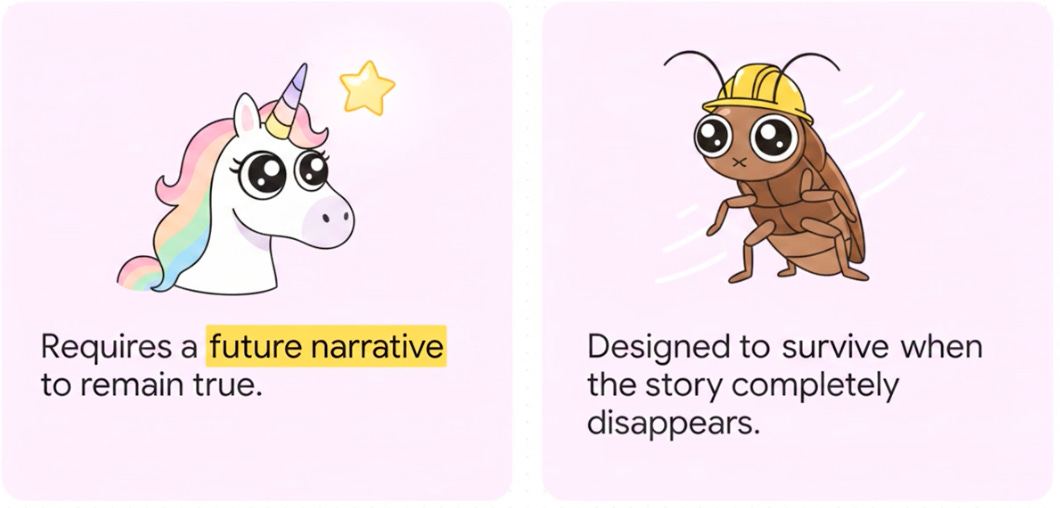
The cockroach, on the other hand, has the structural inversion. Borrowing a term popularized in entrepreneurial circles, the cockroach company is designed around survival rather than recognition. It assumes capital will become scarce, narratives will change, and external conditions will deteriorate. If the unicorn asks whether a story can become reality, the cockroach asks whether the business remains viable when the story disappears.
This essay acknowledges that cockroach carries other meanings. In financial accounting, it already has one, and that meaning is unflattering. Livingstone and Grossman, in the Wiley volume The Portable MBA in Finance and Accounting, use cockroach to describe a kind of restructuring charge. The label comes from the old saying that one cockroach implies many more out of sight. A cockroach charge is a warning because it signals that prior earnings were overstated and that further charges are likely to follow. In that usage, the cockroach is the thing an analyst dreads to find, since finding one means there are others not yet found.
However, this essay uses the word differently, and it takes the definition from the literal biology: the animal rather than from the ledger. Consider what the cockroach actually is. It is decentralized. It survives the loss of its head for weeks because it does not bleed out, it breathes through openings along its body rather than through one airway, and clusters of nerve tissue run its basic functions without a brain to command them. It is low-input. It lasts about a month without food and a week without water, and it can hold its breath for the better part of an hour. It is compressible. It withstands forces approaching nine hundred times its body weight, flattens to a quarter of its height to pass through a gap, and keeps moving while crushed. It is slow, and the slowness is the quiet source of the rest. Its cells divide infrequently, which is much of why it tolerates radiation that kills faster-growing organisms. I am not saying the cockroach survives nuclear war or would inherit the earth. Roaches are not as radiation-resistant as once claimed; they are not the most radiation-tolerant insect, and they would not survive the heat or shockwave of a nuclear blast. But they are “more radiation-tolerant than us, because it grows slowly. But man, who would survive nuclear war anyway!
Read those four traits as a description of a company, and the analogy assembles itself. It has no single point of failure. It depends minimally on external supply. It keeps functioning under pressure. Its endurance comes from growing slowly rather than fast. That is the cockroach this essay means. It is the structural inverse of the unicorn, which depends on continuous capital, a believed story, and a future that arrives on schedule. The cockroach is built to survive the schedule slipping.
The distinction is not about size, sector, or growth rate. It is about epistemic dependency. It is whether a company’s economic foundation requires a particular story to remain true. Put in the language of instruments, the unicorn is an option, priced on a future narrative, while the cockroach is closer to fixed income, an operational engine built on structural necessity that the world needs filled right now. The two trade differently for the same reason that an option and a bond trade differently. And in a correction, the market stops paying for options and starts demanding structural utility.
This became unusually relevant during the AI investment cycle.
Between 2022 and 2024, global AI investment increased from approximately $12 billion to more than $50 billion, a fourfold expansion in committed capital within twenty-four months. During roughly the same period, a 2025 MIT survey and related industry studies reported that 80–95 percent of enterprise AI projects failed to reach production or generate measurable impact. Capital scaled rapidly; realized output scaled less convincingly.
The tension extended beyond the AI sector itself. By June 2026, the Shiller cyclically adjusted price-to-earnings ratio had reached 41.02, having crossed 40 in May for the first time in the cycle. To put that in context, the only month in the previous three decades with a higher reading was December 1999, at the very peak of the dot-com bubble, when CAPE touched 44.2. The current level sits historically just below that mark, in territory associated with speculative excess and large subsequent drawdowns. The signal deserves a caveat that cuts against this essay's own framing. The Shiller ratio averages earnings over the prior ten years, so a company whose earnings grew several hundred percent in the past year alone looks grotesquely overvalued by CAPE while being reasonably priced on any forward measure, because the denominator is still anchored to a decade of pre-AI earnings. Using a backward-smoothing instrument to indict a sector mid-earnings-explosion is a methodological mismatch, and a fair reader should hold the CAPE number loosely for exactly that reason. By May 2026, Deutsche Bank Research reported that the S&P 500 had gained more than 16 percent across April and May alone, a pace observed only four times since World War II. Three episodes were followed by recession, while the fourth preceded the 1987 crash. As The Market Dispatch’s post, Does this mean a crash is coming? observed, the combination of historically elevated valuations, an aggressive Federal Reserve, and widening fiscal deficits made the comparison difficult to dismiss.
The same fragility appeared in market breadth. On the day the S&P 500 reached a record high in May 2026, only 20 of its 500 constituent companies simultaneously reached all-time highs, most of them AI-related. Similar concentration characterized the peak of the dot-com bubble in March 2000. Advance-decline indicators had deteriorated since mid-April, while only 55 percent of S&P 500 companies traded above their 200-day moving average. The index appeared healthy. The distribution did not. Micceri’s observation reappeared in a different form: the aggregate looked normal while the underlying components told a different story.
Questions also emerged regarding the structure of AI financing itself. Servaas Storm, writing for the Institute for New Economic Thinking in December 2025, described the AI data-center investment boom as a collective mania characterized by irrational fear of missing out and structural circular financing: hyperscalers investing in AI companies that use the capital to purchase hyperscaler compute, creating revenue loops that look like growth but are self-referential. Europe Capital Substack note from February 2026 captured this in one sentence: it feels very weird to see Nvidia on all the cap tables and in every investment round, knowing that most of the money will just flow back into their chips.
The coordination was not just cognitive. It was architecturally embedded in the capital structure of the AI ecosystem itself. Microsoft’s March 2026 10-Q offered one illustration. OpenAI is committed to purchasing approximately $250 billion of Azure cloud services through 2030, while Microsoft simultaneously holds roughly 27 percent of OpenAI on an as-converted basis. OpenAI accounted for approximately 45 percent of Microsoft’s $627 billion commercial remaining performance obligations backlog. Capital was not merely entering the system. Portions of it were circulating within it.
At the same time, private skepticism coexisted with public enthusiasm. By mid-2026, SpaceX, OpenAI, and Anthropic were collectively pursuing approximately $3.8 trillion in valuation. Yet a Harvard survey reported that 91 percent of venture capitalists believed unicorn startups were overvalued. That figure can be read two ways, and honesty requires holding both. It may be evidence of the herding this essay describes, professionals privately doubting a price they publicly fund. It may equally be rational behavior: a VC who expects to exit before any correction, and who knows that “overvalued relative to current fundamentals” is not the same claim as “wrong over a ten-year horizon.” The investor who called Amazon overvalued in 1999 was right in the short run and catastrophically wrong in the long run. The survey conflates those time horizons, and the gap between near-term pricing and long-term outcome is precisely the space in which both the cascade and its skeptics can each turn out to be correct.
The first major challenge to these assumptions emerged not from regulators or a market crash but from a Chinese laboratory. DeepSeek, operating with a fraction of the capital available to leading Western competitors, released a frontier-competitive model while reducing API prices by 75 percent. The significance of the event was not merely technological. It demonstrated that some assumptions underpinning prevailing valuations could be questioned sooner than expected.
Taken individually, none of these observations proves the existence of a bubble. Together, however, they present a puzzle.
In an investment cycle where 91 percent of venture capitalists believe unicorn valuations are excessive, where 80–95 percent of AI projects fail to reach production on the first attempt, where market breadth deteriorated beneath record highs, and where the assumptions underlying the largest AI exits were publicly tested before those exits reached the market, what sustained the belief?
More importantly, which companies survive when that belief is tested further?
This essay argues that the answer lies in the interaction between belief and structure. Some firms derive a substantial portion of their value from expectations about a particular future. Others derive their resilience from the ability to survive across many possible futures.
To make that distinction visible, the essay maps the AI landscape onto two animals: the unicorn, whose valuation depends substantially on a particular future being realized, and the cockroach, whose survival does not.
Drawing on research from statistics, behavioral finance, entrepreneurship, and technology markets, together with quantitative evidence from the 2022–2026 AI cycle, the analysis examines why narrative-driven valuation repeatedly emerges, how collective belief becomes embedded in market prices, and which companies remain standing when the assumptions supporting those prices are tested.
This essay would not exist in its current form without Springbok Finance, who pushed back on every figure that looked too clean, supplied the counterarguments this piece needed to survive contact with reality, and tracked down primary sources for claims that started as secondhand Substack chatter. Where this essay is rigorous, it is largely because of that work. Where it is still wrong, that's on us.
And also, special thanks to the Substack community, whose insights and conversations shaped this essay.
Herd Mentality and FOMO in Financial Markets
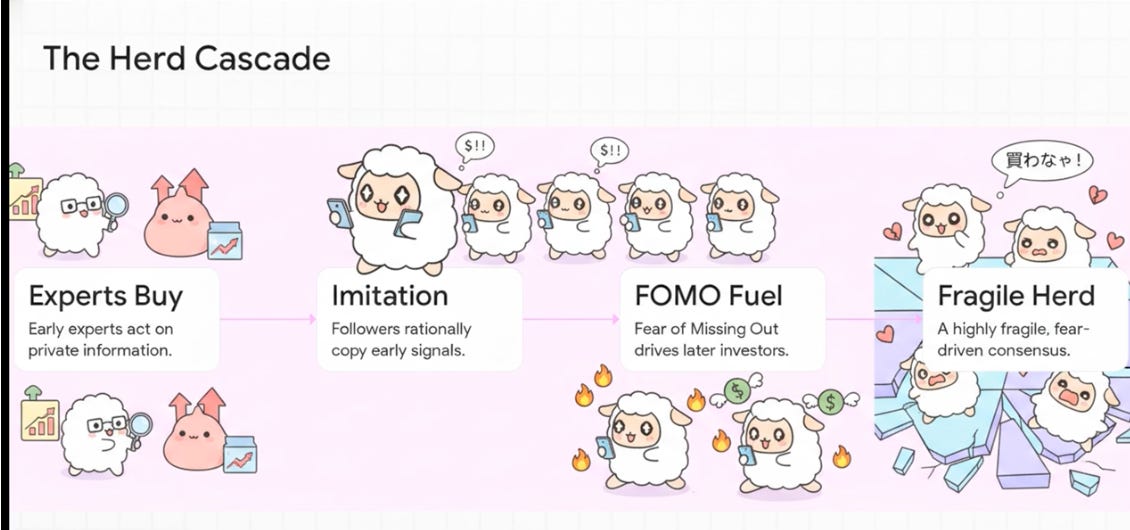
In 1992, Sushil Bikhchandani, David Hirshleifer, and Ivo Welch published “A Theory of Fads, Fashion, Custom, and Cultural Change as Informational Cascades” in the Journal of Political Economy. Its central insight was uncomfortable: rational people, acting on rational incentives, can produce collectively extreme outcomes not because they stop thinking but because they start imitating. Each investor holds private information of uncertain quality. When early investors act on their information and buy, later investors observe those actions and rationally update their beliefs. If enough early investors have bought, it becomes rational for subsequent investors to weight the crowd’s signal over their own, because the cumulative signal from the crowd appears to outweigh any individual’s private assessment. The cascade forms. Once formed, it is self-reinforcing. The catastrophic property of informational cascades is their fragility: because the cascade is built substantially on imitation, it can carry comparatively little fundamental content and can reverse with a small contrary signal.
Bikhchandani et al. (1992) is a theoretical model. The empirical confirmation arrived in 2000, when Welch published “Herding among Security Analysts” in the Journal of Financial Economics. Using 302,458 analyst recommendations from 226 brokers across the 1989 to 1994 period, Welch demonstrated that analyst buy and sell recommendations have a statistically significant positive influence on the next two analysts’ recommendations, that herding towards the prevailing consensus is not stronger when the consensus accurately predicts subsequent stock price movements, and that consensus herding is significantly stronger when market conditions are favorable. This last finding carries the essay’s structural weight: Welch borrowed the term fragility directly from Bikhchandani et al. (1992) to describe the consequence. Bull markets aggregate information poorly. Poorly aggregated information produces a fragile consensus. A fragile consensus is vulnerable to a small contrary signal.
The social psychology foundation beneath the rational cascade model is Asch’s conformity experiments. In 1951 at Swarthmore College, Solomon Asch placed a naive subject in a room with seven confederates and asked them to match a line to one of three obvious comparison lines. When the confederates unanimously chose the wrong line, approximately 75 percent of subjects conformed to the incorrect answer on at least one trial. Not because they could not see the correct answer, but because the social cost of contradiction in public exceeded the cost of being visibly wrong. When Asch ran a variant where subjects wrote answers privately, conformity dropped to 12.5 percent. Financial markets have no private answer sheet.
If Bikhchandani explains why rational investors herd and Asch explains why social animals conform, neither fully accounts for the intensity of the AI investment cycle. The missing mechanism is anticipatory regret. Regret theory was developed simultaneously and independently in 1982 by David Bell in Operations Research and by Graham Loomes and Robert Sugden in the Economic Journal. Both papers made the same foundational observation: people evaluate outcomes not in isolation but against what they could have had if they had chosen differently, and the anticipation of that comparison enters the utility function before the decision is made.
Mohammed Kaddouhah formalized the social dimension of this dynamic in 2024 in Finance Research Letters, providing the first decision-theoretic definition of Fear of Missing Out. FOMO causes individuals to base their decision-making utility on their own anticipated regret and the decisions made by individuals in their social peer group. The avoidance of FOMO by mimicking one’s peer group’s behavior, even when this goes against material interests, means FOMO is formally an explanation for herds. The two mechanisms are not independent. FOMO is the fuel that sustains the cascade after the rational imitation logic has been exhausted.
The institutional dimension of loss aversion reinforces the FOMO mechanism from the other direction. Kliger and Kudryavtsev (2008), writing in the Journal of Financial and Quantitative Analysis, empirically demonstrated that institutional investors display dynamic loss aversion: their risk sensitivity is significantly higher when positions are in loss territory, consistent with Prospect Theory’s prediction that the pain of losses outweighs the satisfaction of equivalent gains. IMD Business School research from June 2025 documented the practitioner consequence: partners who championed deals are systematically inclined to over-reserve follow-on capital for their own positions, using bridge rounds to delay write-downs. FOMO drives the entry. Loss aversion delays the exit.
The AI investment cycle ran the Bikhchandani cascade in textbook form. Early investors with genuine AI expertise moved first. Later investors rationally inferred from those movements that the AI application layer would capture frontier-level margins. In Q1 2026 alone, AI startups raised $255.5 billion globally, but 67 percent went to three deals: OpenAI, Anthropic, and xAI. The information in the cascade was substantially the cascade itself.
THE UNICORN CASES: EPISTEMIC DEPENDENCY IN PRACTICE
The Structure of the Illusion
The 80 to 95 percent failure rate deserves a closer look at the mechanism behind it. Kopp (2026) identified one driver: deal models routinely applied a generic 300-basis-point margin expansion from AI without mapping it to actual P&L constraints. A qualification the data requires: enterprise technology pilot failure rates are historically similar across cloud adoption, ERP implementations, and digital transformation projects. The figure reflects normal technology adoption attrition, not a verdict on AI’s capacity to generate value. Klarna replaced 700 customer service agents with AI. GitHub Copilot demonstrably accelerates developer productivity. Hyperscaler cloud revenue is growing at rates only explicable by genuine enterprise value creation. The failure rate is a data point about deployment difficulty and the gap between ambition decks and P&L reality, not a verdict on the technology itself. The capital was real. The deployment was harder than the projections assumed. The question the market consistently underweighted was who would capture the margin from the AI technology that was genuinely real. The answer, increasingly visible by mid-2026, is: not always the companies that were valued as if they would.
OpenAI: The Purest Unicorn Alive
OpenAI’s revenue has grown substantially. Reported figures for 2025 annualized revenue range from approximately $13 billion (per Wall Street Journal reporting cited by Pollock, 2026) to approximately $20 billion (per Sacra), a range wide enough that even the measurement of OpenAI’s current scale is not fully settled. By either figure, the trajectory is extraordinary. By the Kuckertz framework, it is also the purest expression of valuation outpacing current value creation: the company’s roughly $300 billion to $750 billion valuation range under discussion in 2026 does not rest primarily on those revenues. It rests on the probability of building artificial general intelligence and capturing a meaningful share of the resulting economic surplus.
The burn rate makes this dependency concrete. Internal projections show a net loss of approximately $13.5 billion in H1 2025 alone, with cash burn expected to reach $27 billion in 2026 and $63 billion in 2027. HSBC analysts project OpenAI will not reach profitability by 2030 and estimate a remaining $207 billion funding shortfall to sustain its growth plans. The unit economics remain demanding: inference spend on Azure alone consumed $8.67 billion through Q3 2025, a figure that multiple analyst estimates place close to or above reported revenues for the same period.
The Microsoft relationship is the most important structural fact in OpenAI’s finances, and it is substantially circular. Under renegotiated terms finalized in May 2026, OpenAI committed to purchasing $250 billion of Azure cloud services through 2030, with Microsoft’s IP rights extended through 2032. Microsoft holds approximately 27 percent of OpenAI on an as-converted basis. OpenAI accounts for 45 percent of Microsoft’s $627 billion commercial remaining performance obligations backlog, which nearly doubled year over year. The same money flows in both directions: Microsoft invests in OpenAI, and OpenAI spends that capital on Azure, which appears as Microsoft AI revenue and helps justify Microsoft’s quarterly capex of $30.88 billion, up 84 percent year over year. This is the circular financing structure described by Servaas Storm and confirmed in Microsoft’s own disclosures.
The Microsoft loop is the cleanest example, but it is one node in a wider web. Nvidia agreed to invest up to $100 billion in OpenAI. OpenAI committed to deploy six gigawatts of AMD GPUs and received an option to buy up to 160 million AMD shares. OpenAI signed a roughly $300 billion cloud deal with Oracle, and Oracle in turn spends tens of billions on Nvidia chips. Nvidia, valued near $4.5 trillion, sits at the center, with much of the capital it disburses to its customers returning as orders for its own hardware. Mapped out, the diagram of who funds whom resembles a closed circuit more than a conventional supply chain.
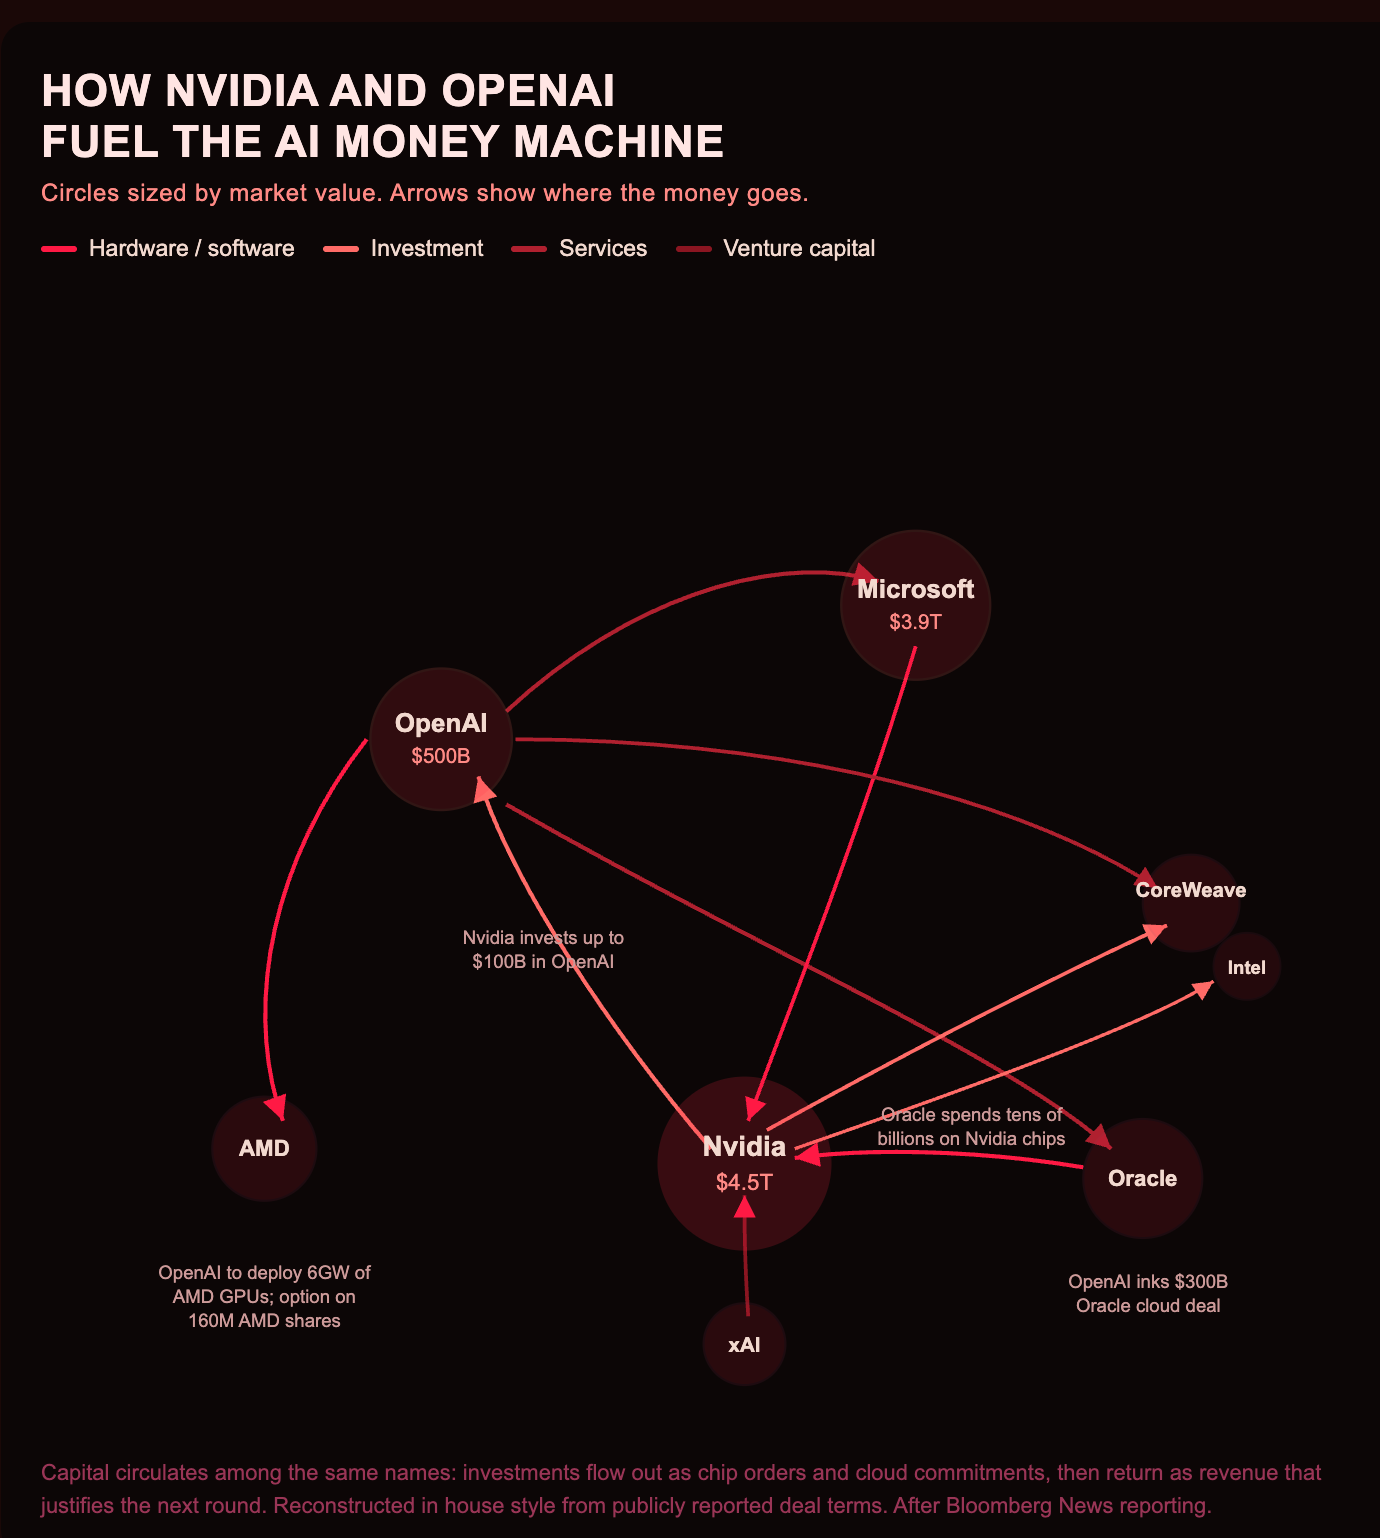
The circularity charge deserves its strongest counterargument, because the charge is easy to overstate. In the early internet era, companies bought Cisco routers with venture money, and a share of Cisco’s revenue was “circular” in the same loose sense, yet the infrastructure that capital built was entirely real and generationally valuable. The scale of the loop also matters: Nvidia’s revenue attributable to OpenAI is only around 10 percent of its total, with the overwhelming majority coming from hyperscalers building physical capacity they will own regardless of which model wins. Calling the whole edifice circular because one revenue stream loops back is closer to calling construction a Ponzi scheme because contractors buy tools. The honest version of the circularity point is narrower: some loops, like Microsoft and OpenAI, are fixed obligations that flatter both companies’ numbers, and those are worth isolating from the genuine end demand around them.
What makes this structure worth dwelling on is what it has done to Microsoft’s own stock, in real time, in the week this essay was written. Microsoft’s AI revenue is now running at a $37 billion annualized rate, up 123 percent year over year. Azure has grown past $75 billion in annual revenue at margins above 46 percent. By the ten-year measure, Microsoft has been one of the great investments of the era: $1,000 invested a decade ago, before the cloud pivot was consensus, would be worth approximately $9,046 today, a return of 804.62 percent, more than triple the S&P 500’s 251.89 percent over the same period. That return was built on Satya Nadella making a bet before the market had organized around it.
The one-year return tells a different story. Over the trailing twelve months, $1,000 invested in Microsoft would be worth approximately $882, a loss of 11.76 percent, against the S&P 500’s gain of 23.38 percent over the same period. Microsoft is down 14.48 percent year to date, including a 10.59 percent decline in the single week before this essay’s reference date, as investors weighed the $30.88 billion quarterly capex bill and OpenAI’s $3.1 billion in Q1 2026 losses attributable to Microsoft against the $627 billion backlog’s eventual conversion to revenue. The bull case is that the backlog converts, and a 21x forward multiple on a business compounding earnings in the twenties is not demanding. The bear case is that the capex cycle outruns monetization before it does.
The ten-year and one-year returns are the same stock, the same company, the same decade-long strategy, measured at two different points in the cascade. The early bet, made before consensus formed around “Microsoft as cloud leader,” tripled the market. The current bet, made after consensus formed around “Microsoft as AI winner via OpenAI,” is currently losing to the market by 35 percentage points. This is Welch (2000) rendered as a single ticker: the informed, pre-consensus position outperformed; the crowded, post-consensus position is underwater, at least for now. Whether it remains underwater is precisely the question the rest of this essay is structured to help the reader think about, not answer for them.
Anthropic: The Doubly Reflexive Case
Anthropic’s revenue trajectory is the fastest documented in enterprise software history, and the company’s own disclosures say so. In its February 2026 Series G announcement, Anthropic reported run-rate revenue growth from $0 in January 2023, to over $100 million in January 2024, to over $1 billion in January 2025, to $14 billion at the time of the announcement, describing this as 10x or greater growth in each of three consecutive years. Six weeks later, in its April 20 2026 announcement of an expanded AWS partnership, Anthropic disclosed that run-rate revenue had “now surpassed $30 billion, up from approximately $9 billion at the end of 2025.” CEO Dario Amodei has said the growth “outstripped the company’s own forecasts by a factor of eight.” By May 2026, some analysts estimated the figure had reached approximately $47 billion.
Laid end to end, the trajectory is not merely steep, it is accelerating within a single year: roughly $9 billion at the end of 2025, $14 billion six weeks later in February, over $30 billion nine weeks after that in April, and an estimated $47 billion roughly five weeks later in May. Each step is a larger percentage increase than the one before it. Claude Code alone, made generally available in May 2025, reached $1 billion in annualized revenue within six months and surpassed $2.5 billion by February 2026, with business subscriptions quadrupling in Q1 2026 and enterprise use now representing over half of all Claude Code revenue. Anthropic disclosed that this growth has strained its own infrastructure: “unprecedented consumer growth” has affected reliability for free, Pro, Max, and Team tier users during peak hours, which the company frames as the reason for its infrastructure expansion rather than the result of it.
The $380 billion Series G valuation, led by GIC and Coatue with participation from BlackRock, Goldman Sachs, Sequoia, Temasek, and others, sits against a run-rate that can reasonably be described as $14 billion, $30 billion, or $47 billion depending on which month in 2026 is used. That is somewhere between an 8x and a 27x revenue multiple on a business still committing substantial future capital to compute. The range itself is informative: a company whose multiple can be quoted as either 8x or 27x depending on a three-month window is a company whose valuation is pricing the slope of the line, not any single point on it.
The AWS relationship mirrors OpenAI’s Azure dependency, with one structural difference worth noting. In April 2026, Anthropic committed more than $100 billion over ten years to AWS technologies, securing up to 5 gigawatts of compute capacity spanning Graviton and Trainium2 through Trainium4 chips, with nearly 1 gigawatt of Trainium2 and Trainium3 capacity coming online by the end of 2026. Amazon’s side of the deal was structured as $5 billion invested immediately, with up to a further $20 billion contingent on commercial milestones, bringing Amazon’s cumulative stake to $33 billion. Microsoft’s $250 billion Azure commitment from OpenAI is a fixed purchase obligation regardless of OpenAI’s performance. Amazon’s additional $20 billion to Anthropic is performance-contingent: if Anthropic’s growth continues, Amazon’s exposure scales with it; if growth stalls, a substantial portion of that capital may not materialize. One hyperscaler built a fixed loop. The other built an option. Both are circular financing. They carry different risk profiles.
What makes Anthropic doubly reflexive is an event that occurred two days before this essay’s reference date. On June 10 2026, the Wall Street Journal reported that OpenAI is weighing significant reductions to the prices it charges for tokens, with one analysis (Pollock, 2026, featuring a January 2026 chart from Oguz Erkan ) framing the move as a response to Anthropic “closing the gap,” with OpenAI “considering using price as a weapon.” Erkan’s chart, built from Anthropic’s own December 2025 projections and OpenAI’s Q3 2025 outlook, shows Anthropic’s optimistic 2029 revenue projection now exceeding OpenAI’s own outlook for itself in the same year. Anthropic targets free cash flow positive by 2028; OpenAI does not expect the same until 2030.
Anthropic’s growth has therefore become the contrary signal applying DeepSeek-style commodity pressure to OpenAI, except this time the pressure originates from inside the Western frontier lab ecosystem rather than from a Chinese laboratory operating at a fraction of the cost. This is the unicorn-cockroach binary applied recursively. Relative to its own $380 billion valuation, Anthropic is a unicorn: the number requires continued belief in a growth rate that even Anthropic did not predict for itself. Relative to OpenAI, Anthropic is behaving like the cockroach: narrower focus, a faster stated path to self-sufficiency, and now actively pressuring its larger, more story-dependent rival to defend its pricing. The cascade does not only reverse from outside the system, as DeepSeek demonstrated earlier. It can also reverse from one unicorn pressuring another, with the more cockroach-like of the two applying the pressure.
The Application Layer: Commoditization From Both Directions
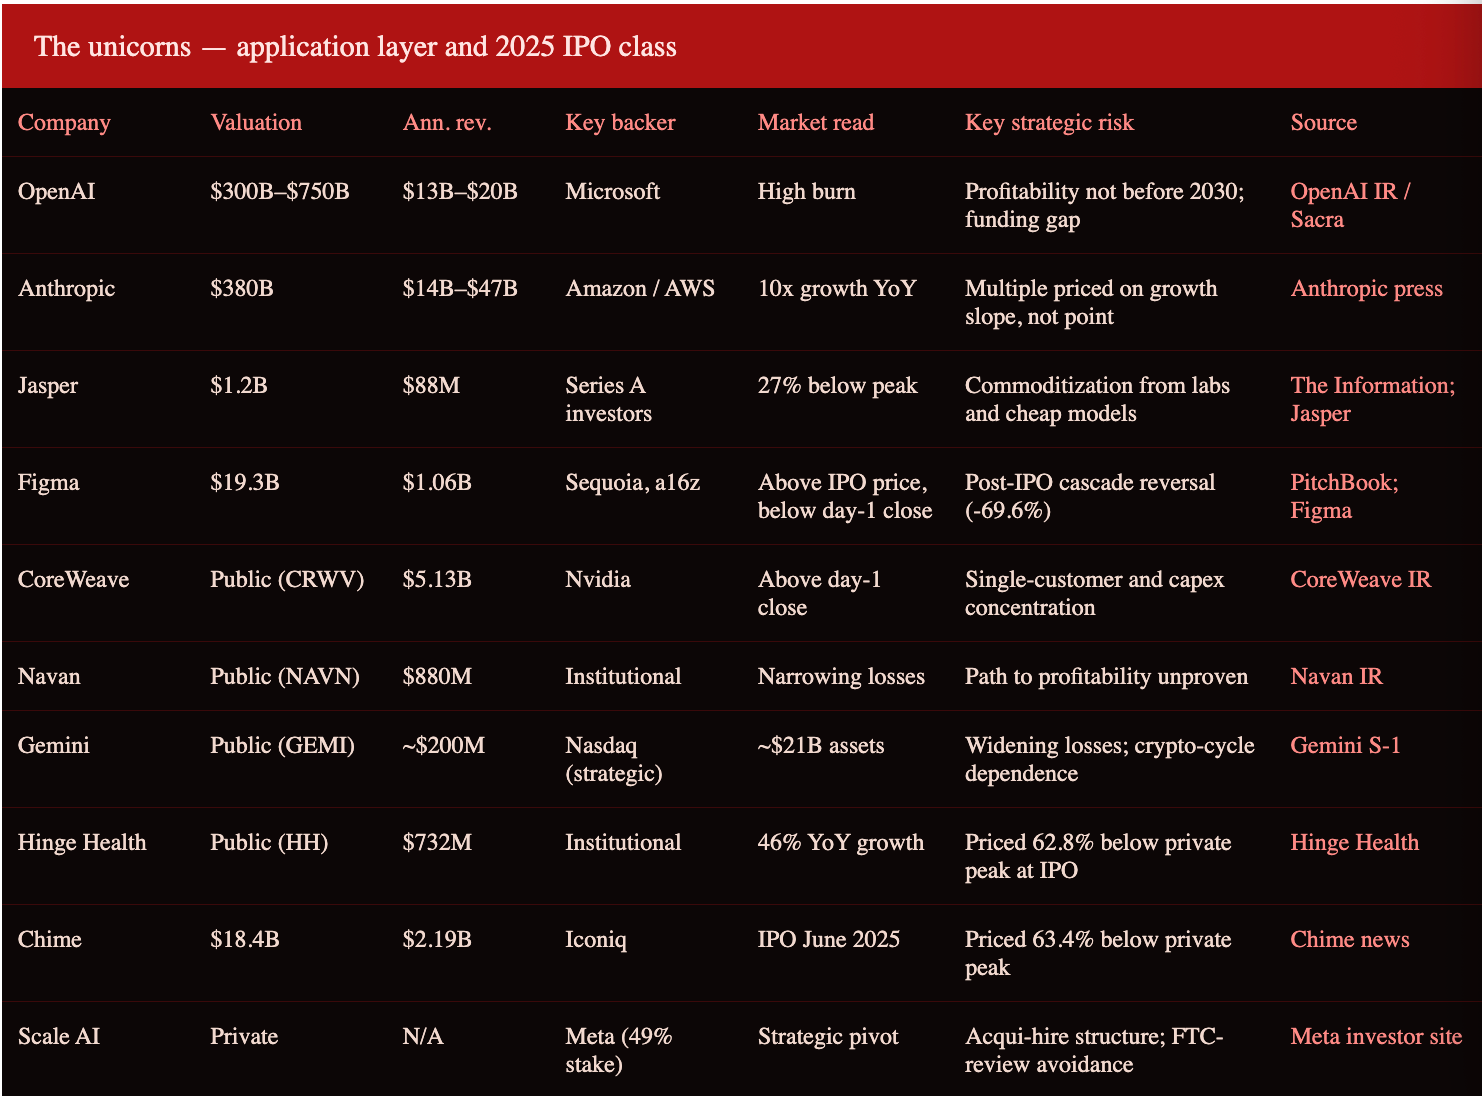
The cleanest case studies in how belief-dependent valuations interact with a commoditizing market are the companies that built on top of the frontier models. Jasper, which became one of the fastest startups to reach unicorn status, raised a $125 million Series A in October 2022 at a $1.5 billion valuation. Its annualized revenue grew from $45 million (2021) to $75 million (2022) to a peak of $120 million in November 2023, at which point the company’s internal share price was cut by approximately 20 percent, implying a valuation closer to $1.2 billion, and CEO Dave Rogenmoser stepped down in favor of former Dropbox president Timothy Young. By mid-2025, revenue had settled at approximately $88 million, roughly 27 percent below its 2023 peak, serving over 100,000 customers including nearly 20 percent of the Fortune 500, at an average contract value of $880.
Jasper is neither a zombie nor a casualty. Its own year-in-review data for 2025 shows a product operating at genuine scale: 76 million content generations, 5,800 custom apps built by users, 2.5 million campaign assets shipped to market, and 82 million images processed through its proprietary models. Jasper’s blog was still publishing product updates in the first two weeks of June 2026. What happened to Jasper is a re-rating: a company priced in 2022 as if it would reach $250 million in ARR by 2024 and continue compounding toward unicorn-scale outcomes, which instead found a durable but smaller equilibrium as a real, profitable-enough enterprise tool. The valuation came down. The product did not go away.
The zombie label, where it does apply, is also worth handling with more care than the bubble framing usually allows. A cohort of underwater unicorns is a normal feature of every technology cycle, not a sign of imminent systemic collapse, and the delay before a write-down sometimes turns out to be correct rather than merely cowardly. After the dot-com bust, a long list of companies extended and pretended, and a few of them, Booking, LinkedIn, and Salesforce among them, went on to become the dominant platforms of the following decade. The zombies that genuinely worry are concentrated in the 2021 vintage of zero-rate generalist startups, the same cohort PitchBook marks at a 68 percent discount, rather than in the AI-native companies funded from 2023 onward with real and growing revenue. Treating those two populations as one is what makes the zombie argument feel more sweeping than the data supports.
The DeepSeek shock introduced earlier is what made this commodity pressure on companies like Jasper arrive publicly rather than only analytically. The same Chinese laboratory had done it on roughly a twentieth of the venture funding available to its Western rivals, which is the detail that turned a pricing event into a narrative one. MrComputerScience writing for Pithy Cyborg in June 2026, put the consequence plainly: each price cut DeepSeek makes erodes the core story that OpenAI, Anthropic, and xAI need Wall Street to keep believing.
This pressure on the application layer is not coming from only one direction. Rohan Mehra, Morgan Stanley’s Head of Global AI Banking, writing in PitchBook’s 2025 Annual US VC Valuations and Returns Report, observed that software companies face “a much higher bar to going public” in an AI-driven world, with historical growth expectations for the sector falling from around 20 percent in 2021, and as high as 30 percent for high-growth names, to roughly 10 percent today. Read alongside DeepSeek, this produces a two-sided squeeze on application-layer software: frontier AI labs are absorbing categories of functionality that used to justify standalone SaaS products from above, while commoditized cheap models are compressing the cost of building competitors from below. Jasper’s trajectory, an early winner that became a smaller, real business rather than either a unicorn or a unicorn’s ghost, may be closer to the median outcome for this layer than either the boom or the bust narratives suggest.
The Broader Cohort: Concentration, Staleness, and the 2025 IPO Class
PitchBook’s 2025 Annual US VC Valuations and Returns Report, published February 10 2026, provides the most precise picture available of how value is distributed across the US unicorn population. At the end of 2025, there were 857 US unicorns with a combined last-reported valuation of $4.7 trillion. PitchBook’s own Valuation Estimates, which adjust for current conditions rather than relying on a company’s last priced round, put the figure at $4.4 trillion, a $300 billion gap that is itself a measure of staleness: the average unicorn last raised capital more than 2.5 years ago, at valuations set under materially different conditions.
Within that population, PitchBook estimates that 222 of the 857 unicorns, just under 26 percent, have likely fallen below the $1 billion threshold since their last priced round. The discount is not evenly distributed by vintage. Companies that last raised in 2021, at the peak of the pandemic-era boom, traded at an average discount of 68.2 percent to their last round in 2025. The 2022 vintage traded at a 52.1 percent discount. The 2023 vintage, which had seemed to have absorbed the correction earlier and was trading at a 16.5 percent premium to its last round as of 2024, had swung to a 19.4 percent discount by 2025, a 36-point reversal in a single year for a cohort that had looked comparatively safe only twelve months earlier.
At the same time, concentration at the top of the market has intensified sharply. The ten largest US unicorns accounted for 53.1 percent of total unicorn value in 2016, falling to a low of 18.5 percent in 2022, the most evenly distributed the market had been in a decade, before surging back to 51.8 percent by 2025, nearly matching the 2016 level. PitchBook attributes this re-concentration explicitly to “standouts like OpenAI and Anthropic,” which “have raised multiple rounds and seen their valuations increase several times over.” The shape of this curve is the AI cycle’s fingerprint on market structure: a decade-low concentration in 2022, immediately followed by the steepest three-year re-concentration in the dataset, driven by the same two companies this essay treats as its central unicorn case studies.
All three of these facts were true simultaneously, as of the same date, December 31 2025: median pre-money valuations for companies that did raise reached decade highs, exceeding even 2021 levels; nearly 15 percent of all VC rounds were completed at flat or down valuations, close to a decade high; and the top ten companies controlled more of total unicorn value than at any point since 2016. The market for the perceived winners and the market for everyone else were, by these numbers, behaving as two different markets.
The 2025 IPO class makes the same point from the exit side. Of 48 companies that completed IPOs in 2025, the median step-up for public listings was 0.97x, meaning the typical company went public below its most recent private valuation. Fourteen of the seventeen unicorns that went public in 2025, 82 percent, priced below their last private round. Selected step-downs from private peak to IPO valuation: Chime Financial, negative 63.4 percent; Hinge Health, negative 62.8 percent; Gemini Space Station, negative 59.8 percent; Navan, negative 40.7 percent; CoreWeave, negative 22.3 percent; Circle, negative 16.4 percent; Netskope, negative 15.3 percent. A smaller group priced above their private peak: Wealthfront at positive 24.8 percent, Figure Technology Solutions at positive 44.5 percent, Figma at positive 56.7 percent, and BETA Technologies at positive 64.9 percent.
Figma’s case is worth dwelling on as a preview of the SpaceX section that follows. Figma’s stock surged approximately 250 percent on its first day of trading in July 2025, then fell 69.6 percent from that first close by December 31 2025. A cascade formed and reversed within six months, fully visible in a single company’s share price. CoreWeave presents the inverse pattern: down 22.3 percent against its private-market peak, but, unusually among the 2025 cohort, trading above its own first-day close by year end, the only company in PitchBook’s sample to do so. CoreWeave’s private valuation may have been the unicorn fiction; its public valuation, while still a step down from that peak, has so far proven more durable than its peers’. Neither pure unicorn nor pure cockroach, CoreWeave is a useful reminder that the binary is a lens, not a label that stays fixed once applied.
One further mechanism from the PitchBook report deserves a place alongside the p-value framework above. In December 2025, Nvidia announced a $20 billion “non-exclusive licensing agreement” with Groq that, per PitchBook, “effectively transferred Groq’s assets and senior leadership without a traditional acquisition.” Meta’s $14.3 billion investment for a 49 percent stake in Scale AI in June 2025 similarly included the hiring of the company’s founder and key personnel. Both transactions achieve the practical effect of an acquisition while avoiding the formal label that would trigger FTC review. This is the p-hacking described earlier, applied to M&A: the underlying event is the same regardless of label, but the label is engineered to avoid clearing a regulatory threshold, in the same way a researcher might engineer an analysis to avoid or achieve a p-value threshold. The form changes. The substance, and the concentration it produces, does not.
THE COCKROACH CASES: STRUCTURAL INDIFFERENCE TO BELIEF
TSMC: The Cockroach Under Every Floorboard
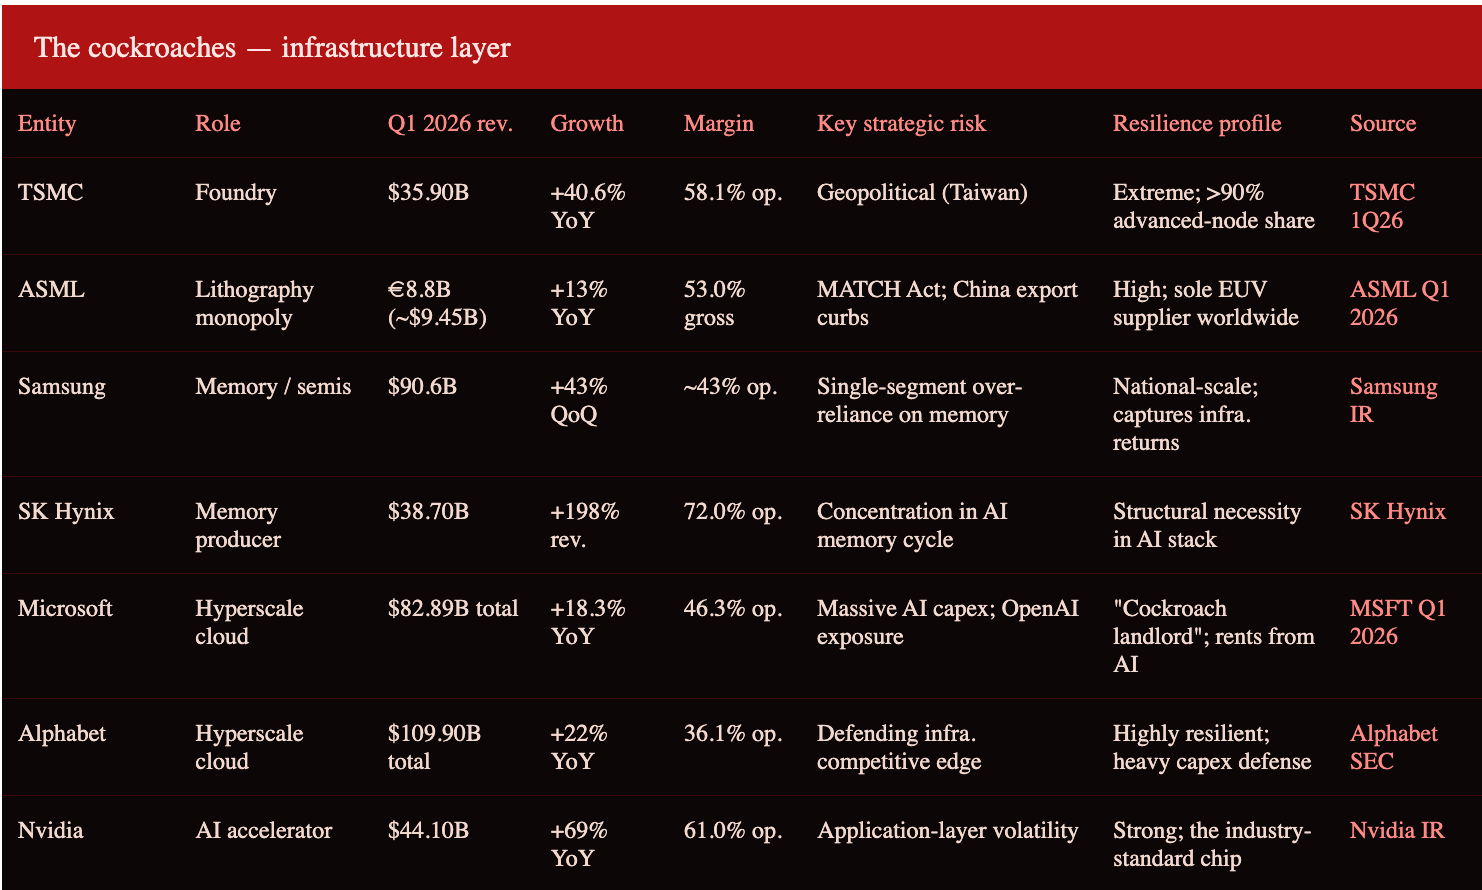
ASML manufactures the extreme ultraviolet lithography machines without which no leading-edge chip can be produced. There is one company in the world that makes these machines. Q1 2026 financials: total net sales of €8.8 billion, roughly $9.45 billion, up about 13 percent year on year, net income of €2.8 billion, gross margin 53.0 percent. Full-year 2026 guidance was raised to €36 to €40 billion, implying up to 22 percent growth over 2025.
The cockroach case for ASML carries one honest caveat, and it is worth stating precisely because it is the strongest test of the thesis in this section. China represented a record 33 percent of ASML’s 2025 revenue. ASML had already guided China down to approximately 20 percent of 2026 sales because of existing export restrictions. A bipartisan bill in the US Congress, the MATCH Act, proposes to extend restrictions beyond EUV machines to ASML’s less-advanced DUV immersion systems, and, more significantly, to ban servicing, calibration, and spare parts for DUV equipment already installed in China, which would cause that installed base to degrade over time rather than simply stop growing. Allied nations, including the Netherlands and Japan, have a 150-day window to adopt equivalent measures before unilateral US action would take effect.
ASML’s own management has stated that if the MATCH Act’s restrictions fully materialize, sales could be pushed to the low end of the already-raised €36 to €40 billion guidance range, a swing of roughly €4 billion. The cockroach case survives this test in a specific and informative way: even in the scenario where ASML loses roughly two-thirds of its largest single national market to geopolitics, in addition to the reduction already priced into guidance, the company’s full-year guidance was still raised, not lowered, because non-China demand for AI-driven capacity expansion, including from TSMC, is large enough to backfill the loss. ASML’s EUV monopoly remains structurally intact; no competitor has shipped a comparable machine. The cockroach is real, but in this case, it is also a useful illustration of the earlier qualification: it survives, but it can scar, and the scarring is geopolitical rather than economic.
The Hyperscalers: Cockroach Landlords
Amazon Web Services, Microsoft Azure, and Google Cloud occupy the most structurally advantaged position in the entire AI stack. They are the infrastructure that AI applications run on, which means they capture value regardless of which AI application wins. OpenAI needs Azure. Anthropic needs AWS, increasingly including AWS’s own Trainium silicon rather than only third-party chips, which deepens the relationship from cloud-rental circularity into a manufacturing relationship as well. Every AI unicorn in the application layer is paying rent to the hyperscalers. Microsoft, Amazon, Alphabet, and Meta are expected to invest a combined $650 billion in AI infrastructure within a single year, with 2026 capex guidance of $145 billion, $200 billion, $180 billion, and $125 billion, respectively, much of it directed toward data centers, chips, networking, and energy. The figure is worth holding next to the disclosed AI-attributable revenue these companies report, because the gap between the two is the clearest single measure of how far ahead of monetization the buildout currently runs. This is the infrastructure spending of companies that have already captured the position they are investing in to defend. The unicorn raises money to reach a position. The cockroach spends money to reinforce one it already holds.
Analyst Rating Distribution: The Cockroach Was Already Consensus
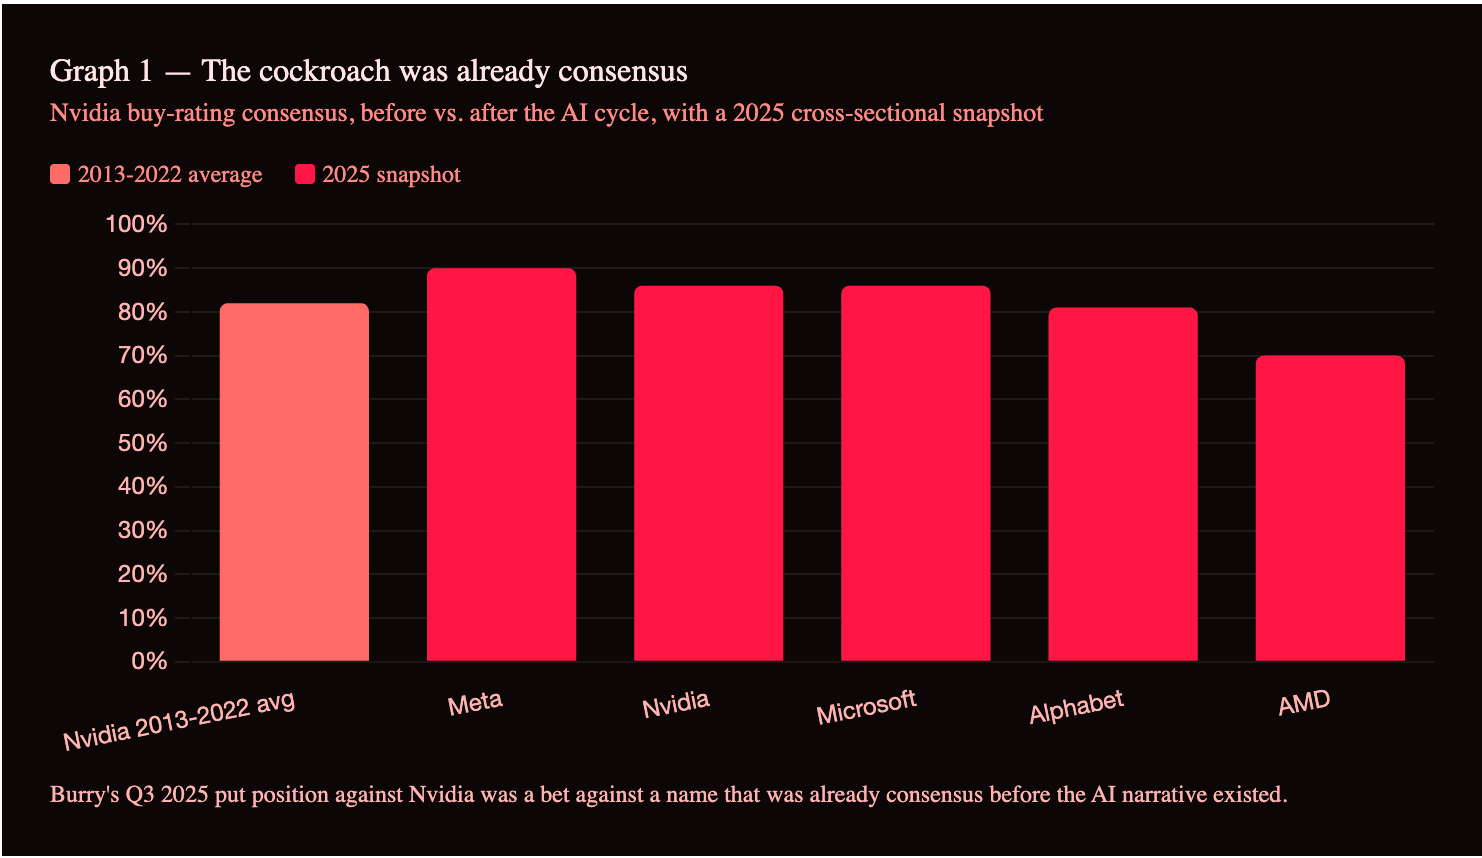
Analyst rating distribution is the most direct quantitative measure of cascade density, and the data here tells a more specific story than “the herd piled in.” Bank of America’s own historical figures show Nvidia’s buy-rating consensus averaged 82 percent from 2013 to 2022, before the AI cycle began. By 2025, seven independent sources, MarketBeat, Benzinga, StockInvest, SEC 13F filings via CNBC, ChartMill, S&P Global, and Investing.com, converged on a buy-rating consensus for Nvidia of 85 to 87 percent: an increase of roughly four to five points.
The infrastructure layer was not discovered by the AI cascade. It was already close to maximum consensus before anyone called it an AI story. What the cascade did was compress dispersion within the AI-adjacent basket rather than create belief from nothing: as of the 2025 snapshot, Meta sat at 89 to 90 percent buy ratings, Nvidia and Microsoft both at 85 to 87 percent, Alphabet at 80 to 82 percent, and AMD at 70 percent, fifteen to twenty points below its nominal peers. Michael Burry’s Q3 2025 purchase of more than $1 billion in put options against Nvidia and Palantir is, in this light, a bet against a name that was already consensus before the AI narrative existed, which makes it a more notable act of dissent, not a less notable one. The Asch room was quiet about the infrastructure layer for over a decade. The AI cycle made the room slightly quieter still and concentrated the noise in AMD, the one name in the basket where consensus has not fully formed.
THE SPACEX IPO: BOTH CREATURES SIMULTANEOUSLY
Joe from The M&A Hunter identified an angle on the SpaceX IPO that pure valuation analysis misses entirely: the gravitational force of a multi-trillion-dollar belief event not only affects the IPO’s own investors. It displaces capital across other asset classes simultaneously. Documenting the historical pattern from Meta in 2012, Alibaba in 2014, and Uber in 2019, he showed that when mega-IPOs hit the market, small-cap biotech sold off in the immediate weeks as capital rotated into the consensus must-own name, then recovered strongly one to three months later.
The companies with real M&A catalysts, real cash positions, and real binary FDA events get sold not because anything about them has changed but because the unicorn requires liquidity and the market provides it by taxing every other asset class temporarily. The cockroach recovers because the thesis was never the narrative.
Joe published another companion note, “Profitable IPOs vs. Hype IPOs: Why the Difference Matters,” the day after his SpaceX week-ahead note, without naming SpaceX directly in either. His framework distinguishes the profitable IPO, which “comes public with real revenue, growing earnings, and a business model that already works,” from the hype IPO, which “arrive[s] with a massive total addressable market, exciting growth projections, and little or no profitability.” His concluding line states the cockroach thesis as a trading rule in two sentences: “Profitable IPOs remove uncertainty early. Hype IPOs ask investors to trust a future that has not arrived yet.”
The SpaceX IPO is the essay’s live case study, and it is the richest one precisely because it contains both creatures at the same time. The operations are substantially a cockroach. The valuation is substantially a unicorn. The index funds are the herd. Figma, six months earlier and at a much smaller scale, already showed what happens when these elements interact: a 250 percent first-day surge followed by a 69.6 percent decline from that first close within six months. SpaceX is the same mechanism, scaled by roughly three orders of magnitude.
The Macro Frame: $3.8 Trillion of Belief
The SpaceX IPO is not arriving in isolation. It is one-third of the $3.8 trillion already mentioned, alongside OpenAI and Anthropic, each built on a version of the same shared narrative: that the companies at the frontier of artificial intelligence are building something scarce, defensible, and worth a premium the market has not previously assigned to any technology at this scale.
Financial Fables writing on June 7, 2026, in “AI and Tech IPOs: Force Feeding Investors,” used Dealogic data to show that the combined SpaceX, OpenAI, and Anthropic IPO scale would exceed every prior tech IPO in history, including Facebook, Alibaba, and Uber, occurring in the same calendar year.
As MrComputerScience observed in June 2026, DeepSeek’s demonstration that frontier-level intelligence can be engineered at a fraction of Western venture capital cost means the category premise is already under pressure at the precise moment the three largest exits in AI history are being brought to market.
The Cockroach Underneath
SpaceX filed its S-1 with the SEC on May 20, 2026, offering 555.6 million shares at $135 each, targeting a $75 billion raise at a $1.77 trillion valuation, with trading expected on Nasdaq under the ticker SPCX around June 12, 2026. Goldman Sachs leads a syndicate of 21 banks. Retail investors are allocated 30 percent of the float, three times the standard mega-cap norm. Elon Musk holds 42 percent of equity and 85 percent of votes.
The operational reality, drawn directly from the S-1, is unambiguous. Total 2025 revenue: $18.674 billion, up 33 percent from $14.1 billion in 2024. Adjusted EBITDA: $6.584 billion. The Connectivity segment, primarily Starlink, generated $11.387 billion in revenue, 61 percent of the total, with $4.423 billion in operating income and $7.168 billion in segment adjusted EBITDA, a 63 percent margin, representing year-over-year growth of 49.8 percent, 120.4 percent, and 86.2 percent, respectively. Subscribers grew from 4.5 million at the start of 2025 to over 9 million by year-end to 10.3 million by Q1 2026, across 164 countries and more than 9,600 satellites, representing roughly three-quarters of all active maneuverable satellites in low-Earth orbit. SpaceX launches more than 80 percent of all mass to orbit globally, with cadence increasing from 98 launches in 2023 to 170 in 2025.
The Space segment, consisting primarily of Falcon 9 launch services, generated $4.086 billion in revenue in 2025 with a $657 million operating loss and a positive segment adjusted EBITDA of $653 million, the loss being attributable to approximately $3 billion in Starship research and development being expensed rather than to weak unit economics in the launch business itself. The launch segment, in other words, is also closer to cockroach than unicorn on an underlying basis; its reported loss is a reinvestment choice, not a structural deficiency.
The Unicorn On Top
The AI segment tells the opposite story, and it is the segment responsible for SpaceX’s swing from profitability to loss. In 2024, before the xAI merger was completed in February 2026, SpaceX was net-income positive at $791 million. In 2025, with xAI consolidated, SpaceX reported a GAAP net loss of $4.937 billion, with the AI segment alone generating $3.201 billion in revenue against a $6.355 billion operating loss, driven substantially by approximately $12.7 billion in xAI-related capex. The accumulated deficit reached $41.3 billion, and the Q1 2026 net loss alone was $4.28 billion.
SpaceX did not become unprofitable because its rockets got more expensive or Starlink’s growth slowed. It became unprofitable because it acquired a unicorn, and the unicorn’s losses are now larger than the cockroach’s profits.
At $135 per share and a $1.77 trillion valuation, SpaceX is priced at approximately 94 times its 2025 revenue and 266 times its 2025 adjusted EBITDA. Those multiples are arresting, but they are not, on their own, the argument. Aswath Damodaran makes this point across two posts, and it is worth taking seriously precisely because he is a valuation purist rather than a hype merchant.
In April 2026, before the prospectus, Damodaran valued SpaceX at roughly $1.22 trillion, with a simulation median near $1.29 trillion, and predicted that analysts unable to justify the pricing on trailing numbers would resort to “pricing gymnastics with forward multiples, hand-picked peer groups and fairy tales.” In his June 5 post-prospectus update, he ran the valuation again on the real filing and barely moved: enterprise value roughly $1.22 trillion, equity $1.25 to $1.35 trillion, which works out to an intrinsic value of about $98 per share against the $135 offering price, and against the roughly $1.8 trillion the offering implies for the company. Notably, he calls the headline bear case, that SpaceX is money-losing, cash-burning, and trading at a hundred times revenue, both “lazy and unconvincing,” noting that investors who refuse to buy loss-making companies “will end up with portfolios of mature and declining businesses.” The legitimate case against the price, in his framing, is not the multiple. It is whether the target markets are as large as claimed, whether margins survive competition, and whether a voting structure that locks in Musk’s control will restrain a company inclined to overreach in AI.
That last point is where the prospectus does its most revealing work. Its stated total addressable market is $28 trillion, of which $26 trillion is AI, a figure Damodaran calls bordering on “fantasy” and compares to the gamified TAMs floated for Uber ($5.7 trillion) and Airbnb ($3.4 trillion) at their own offerings. He also flags a detail that links SpaceX directly to the Anthropic case discussed earlier: Colossus, xAI’s compute center, has been leased to Anthropic for roughly $1.25 billion a month, a circular-financing thread running from one of this essay’s unicorns straight into another. His takeaway is that the prospectus made the story “bigger, but also more volatile,” with the risk he weighs most heavily being overreach in AI, “funded by tens of billions of dollars of shareholder money.”
Ed Elson , writing for Prof G Media in May 2026, “SpaceX-stasy, found that AI gets a mind-boggling 1,251 mentions in the prospectus, alongside other sci-fi buzzwords ("first principles" 27 times, "light of consciousness" 10 times). He also dismantles the company's claim of a $28.5 trillion total addressable market, noting that $26 trillion of it is attributed strictly to AI rather than to the actual space or satellite businesses. Set beside that $26 trillion AI TAM, the pattern is the same one this essay keeps returning to: the label is doing coordination work, in the same sense that a p-value does coordination work. It is the threshold the market has agreed to treat as significant, attached to whichever part of the business currently clears it most easily.
The Herd Becomes Structural
Force Feeding: When FOMO Becomes Compulsory
Financial Fables provided the most complete account of how passive investors lose the ability to opt out of the AI belief cycle, however, they might individually assess it. Their metaphor: a diner who is full and ready for the bill, served another course regardless.
The mechanism is a specific regulatory change. In April 2026, S&P Dow Jones began consulting on a rule change that would exempt megacap IPOs from the profitability and seasoning requirements that currently gate S&P 500 inclusion, shortening the seasoning period from 12 months to 6. Size would substitute for the track record that the existing rules were designed to require.
The arithmetic of index composition, if SpaceX, OpenAI, and Anthropic were all included near their discussed valuations, would put all top 10 index constituents in technology, with those ten names representing close to 40 percent of the index.
Financial Fables documented the broader exposure expansion across asset classes: S&P 500 technology exposure rose from 18 percent in 2015 to 38 percent in 2026; MSCI Emerging Markets from 28 percent to 50 percent; and US investment-grade corporate bonds from 10 percent to 16 percent. A portfolio that looks diversified across equities, emerging markets, and fixed income may increasingly be the same bet expressed three times.
The Structural Herd: Index Mechanics as FOMO Architecture
Lawrence Fossi and John H. Cochrane , writing in June 2026, described the mechanics of index-fund demand: funds are required to buy shares of newly included large companies in proportion to market capitalization, a form of demand that does not respond to price and can therefore amplify moves in either direction.
Phil Bak and Chris Irons framed the SpaceX IPO as a referendum: overwhelming demand would confirm the broader belief; disappointing demand could mark a turning point for the cycle
Jay Kuo added the compulsory-ownership angle: passive index investors would be exposed to SpaceX whether or not they individually believe in it, which is a different and stronger claim than ordinary FOMO. It is not the fear of missing out. It is the structural inability to opt out.
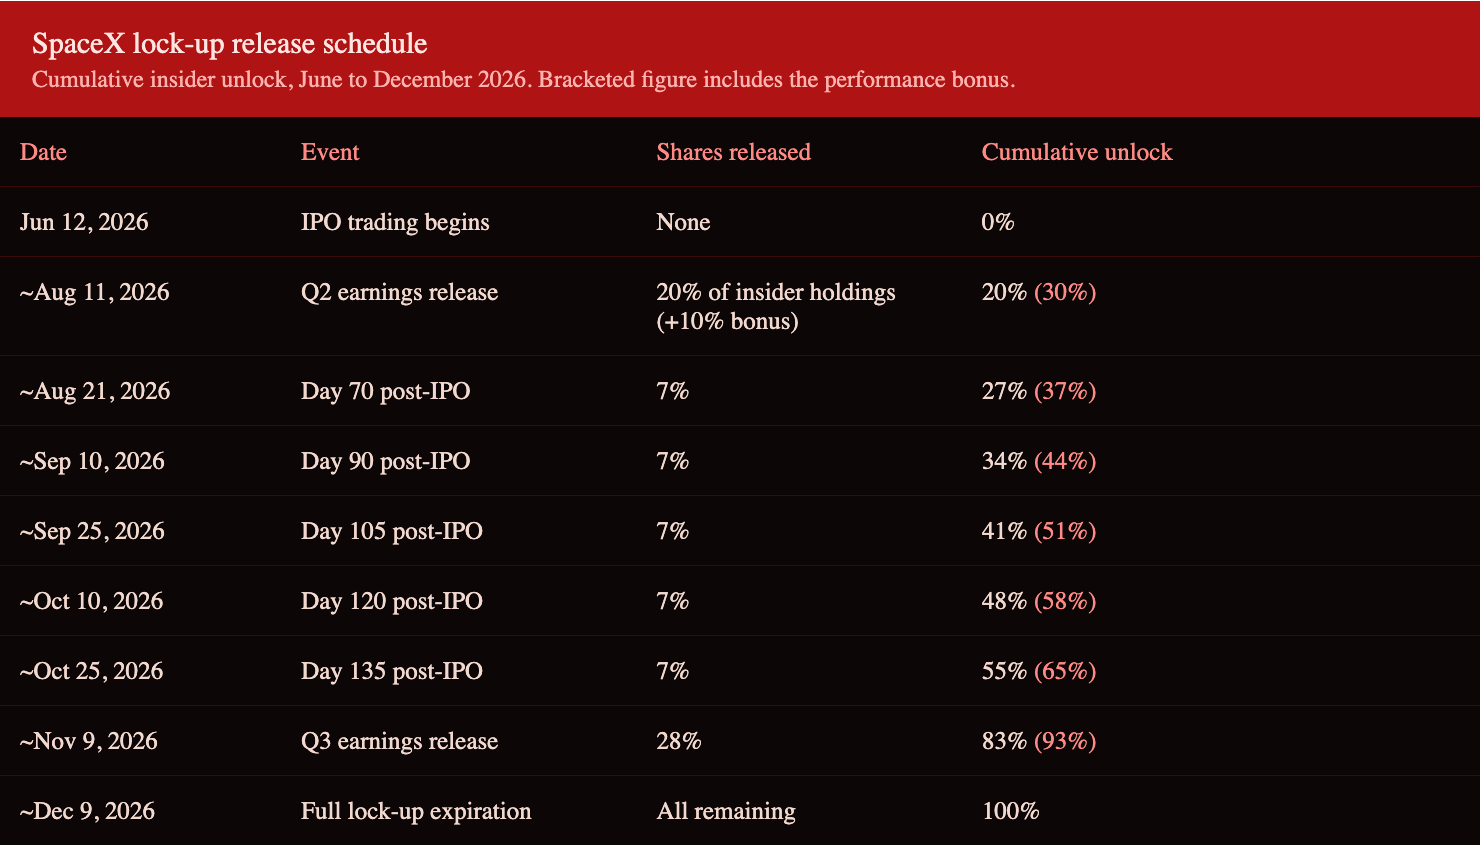
There is a supply-side counterpart to all this forced demand, and it has a calendar. Joe from The M&A Hunter mapped SpaceX's lock-up structure and found not a single cliff but a staggered release: zero insider shares free to trade at the June 12 listing, then a first tranche of roughly 20 percent unlocking around Q2 earnings in August, followed by a sequence of 7 percent releases through the autumn and a large 28 percent block at Q3 earnings in November, reaching full expiration by around December 9. A performance bonus accelerates the schedule, unlocking an extra 10 percent early if the stock trades at least 30 percent above its IPO price for 5 of any 10 consecutive trading days. The structure is worth pausing on because it sets price-insensitive index demand at the listing against a rising tide of insider supply over the following six months. The herd is required to buy at the moment supply is most constrained, and the constraint loosens precisely as the cascade has had time to mature. Whether the staggered design dampens the post-lock-up drawdown that megacap IPOs typically suffer, or merely spreads it across more dates, is one of the open questions the next two quarters will answer.
The Herd Becomes Measurable
Retail Inflow Data: The FOMO Measurement
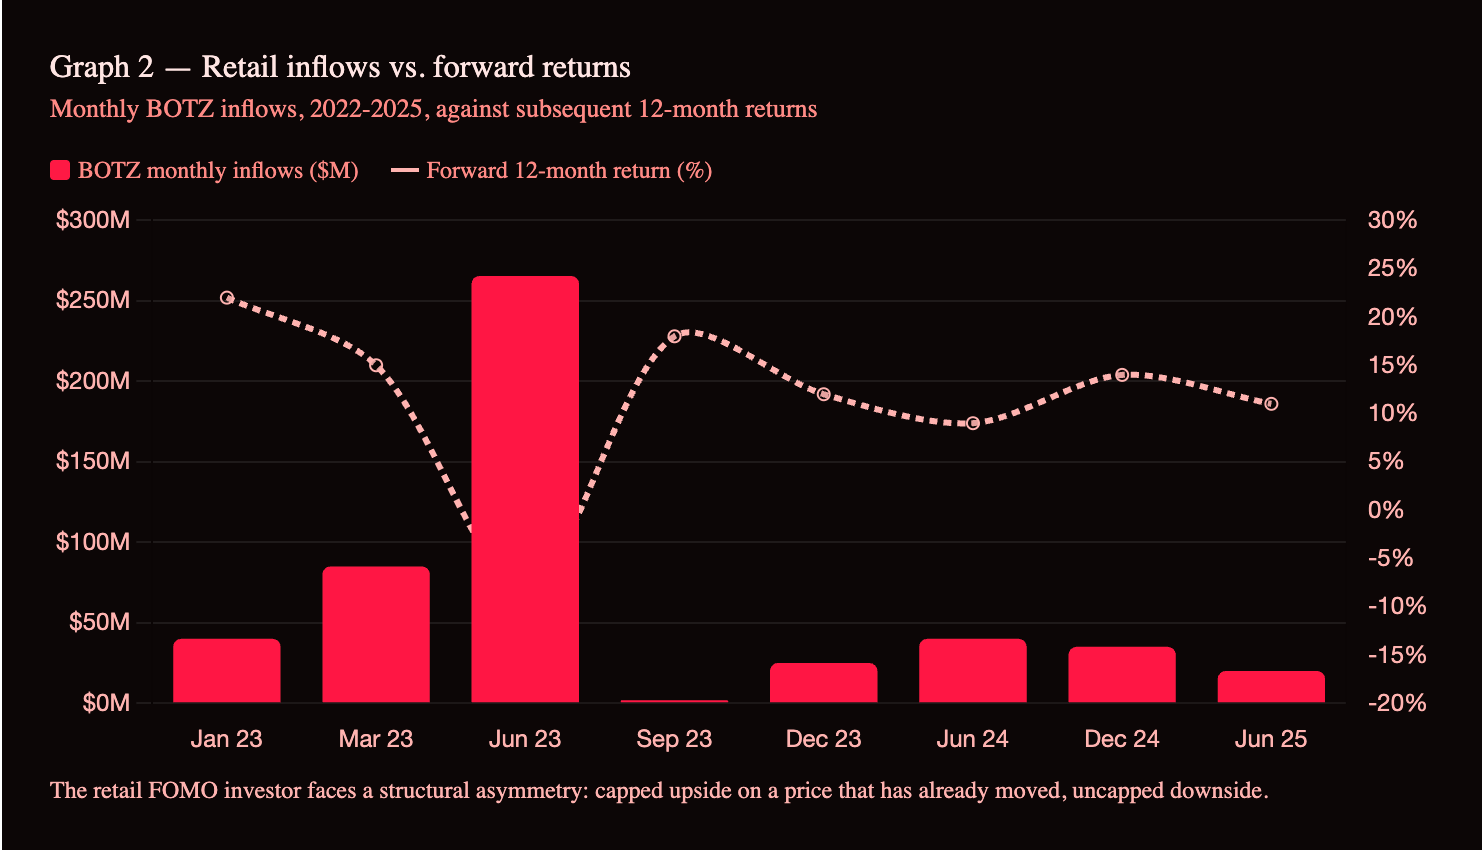
Retail inflow data measures the democratization of the herd. Kaddouhah (2024) showed formally that FOMO causes individuals to weight anticipated regret and peer behavior into their utility function.
BOTZ received its highest monthly inflows of 2023 in June 2023, $265.5 million, immediately after the ChatGPT enthusiasm peak; by September 2023, inflows had dropped to $1.8 million. AIQ reached $7 billion in AUM by November 2025.
The asymmetry the retail FOMO investor faces is structural: the upside is capped by a price that has already moved, while the downside is not.
The QF-MI Quantum Fields Market Intelligence note from June 2026 documented a cascade-reversal event in which the AI capital complex lost $1.3 trillion in a single Friday, with the AI physical infrastructure complex selling off as a single trade regardless of individual company merit. When the herd moves, it moves the basket, not the names.
The Herd Becomes Concentrated
The concentration process does not stop at capital flows. It becomes visible inside the valuation itself.
By the cockroach test, Starlink’s operations pass with distinction. Sergey writing for Compounding Your Wealth note in June 2026, provided the most granular decomposition available of what the headline valuation actually contains.
By his analysis, Starlink as a standalone business is worth approximately $450 billion in a base case and $500 to $650 billion in a bull case, derived from a mid-2026 annualized revenue estimate near $13 billion representing roughly 75 percent of SpaceX’s total EBITDA.
If Starlink alone justifies $450 to $650 billion, the remainder of the $1.77 trillion valuation, somewhere between $1.1 and $1.3 trillion, is being assigned to the Space launch segment, Starship development, the AI segment, the X platform, and the orbital AI compute narrative.
The cockroach has, in effect, been valued separately. Everything above that figure is the unicorn.
Morningstar published an independent DCF valuation of $780 billion, roughly 55 percent below the IPO target, describing SpaceX as “significantly overvalued” with an “indeterminate” economic moat, and singling out the xAI merger, which Musk both negotiated and approved, as a “material threat of value destruction.” This is one of the few formal sell-equivalent initiations on a mega-IPO, set against a 21-bank underwriting syndicate with structural financial incentives to support the deal.
The spread between the honest estimates is itself the story. Morningstar’s DCF lands at $780 billion, Damodaran’s at $1.25 to $1.35 trillion, and the market at roughly $1.8 trillion. Three serious attempts to price the same company, run on the same prospectus, diverge by more than a trillion dollars. The disagreement extended past valuation into governance: AkademikerPension, a Danish pension fund, placed SPCX on its investment blacklist over what it called catastrophic governance, while passive index funds were obliged to buy the same stock regardless of price. When the disagreement among careful allocators is that wide, the number the market settles on is not a measurement. It is a vote.
The historical base rate for this kind of exposure is sobering on its own terms. Mulberry Investment Research publishing a June 9, 2026, Substack Note citing Bloomberg and Truist data, found that the one-year average price return from IPO price for megacap tech IPOs is less than 5 percent, while first-year maximum drawdowns of 30 to 80 percent are common. As one reader summarized the chart in the same Notes thread: the hype is loud, but a sub-5 percent average return is the data being quiet about it.
The Herd Becomes Narrative
The Musk Flywheel and the External Rotation
Nikhs in a June 2026 Substack note titled “SpaceX and the Price of Belief,” described a “Musk Flywheel” in which belief becomes narrative, narrative attracts capital, capital funds capacity, capacity produces proof, and proof reinforces belief, an informational cascade engineered deliberately as a business model.
His price targets for SpaceX range from $60 to $90 per share in the bear case to $350 to $500 in the bull case, framed explicitly not as predictions but as descriptions of which state of belief the market currently occupies.
The M&A Hunter ‘s rotation thesis applies directly here: capital flowing into the SpaceX IPO has to come from somewhere, and historically it has come temporarily from small-cap biotech and similar sectors, which then recover once the rotation completes.
Stephen McBride of the Rational Optimist Society represents the opposite end of the spectrum, framing the missing SpaceX IPO as comparable in social cost to missing a Harvard admission, an articulation of FOMO from inside the belief rather than about it.
MrComputerScience added one observation that cuts across every valuation framework in this section: seven of nine Tesla data labelers, the people who train the Full Self-Driving models daily, said in 2026 that they would not trust the software to drive them. The people building the system are sometimes the first to revise their beliefs about it; the cascade’s tail is often the last to know.
The Herd Meets Dissent
Short Interest: The Contrarian Measurement
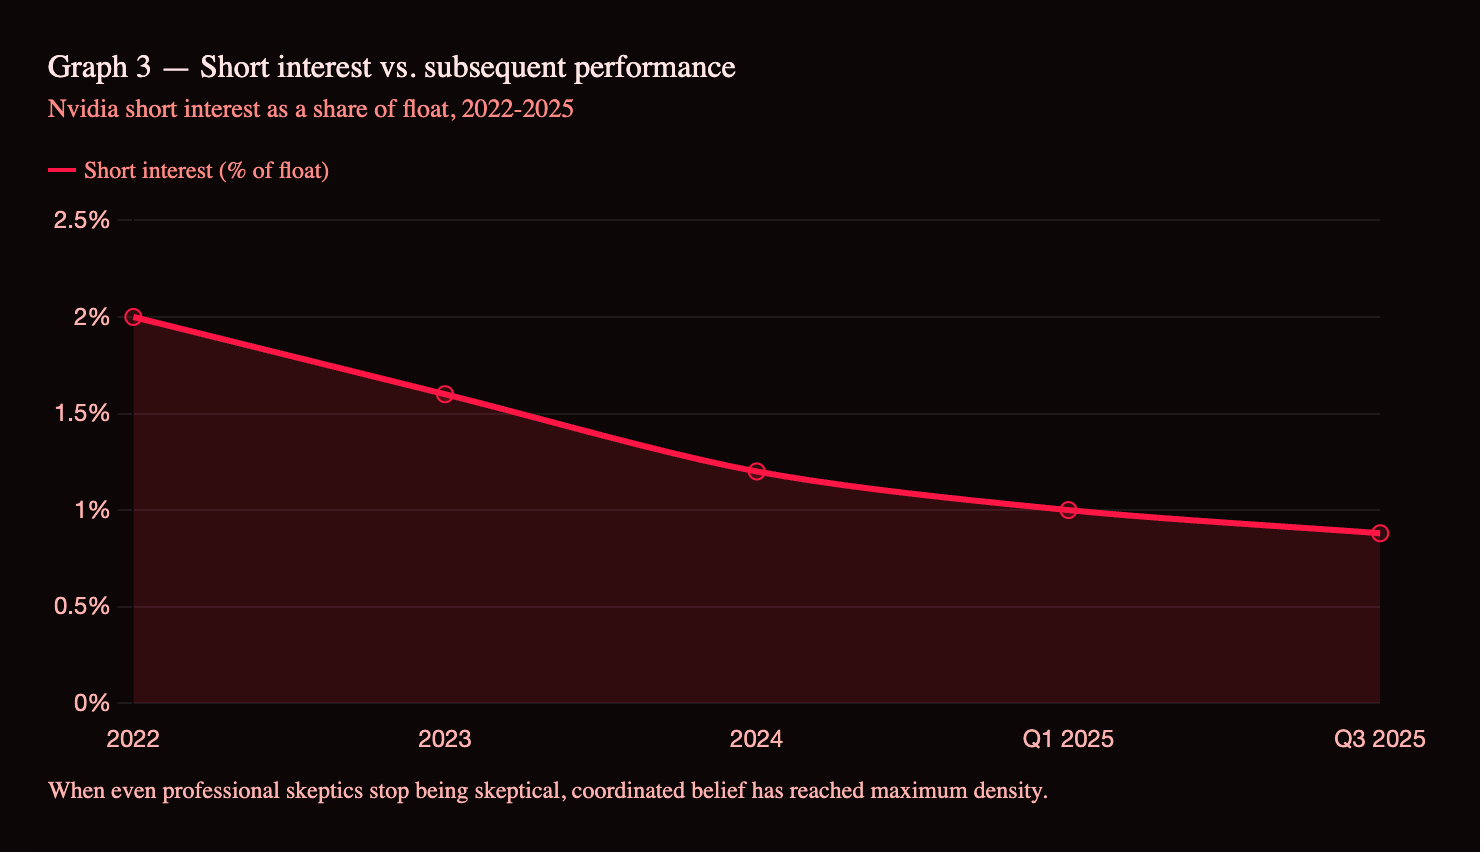
Short interest is the contrarian signal: when even professional skeptics are not skeptical, coordinated belief has reached maximum density.
Nvidia’s short interest stood at 0.88 percent of float in August 2025 at a market capitalization of roughly $4.5 trillion. Burry’s put position is, again, one of the few documented institutional bearish positions against this name.
The Anomaly Investment Partners note from June 2026, applying standard financial ratios to the AI unicorn cohort and finding the arithmetic difficult to reconcile with current prices, represents the skeptic voice that low short interest tends to suppress in formal coverage.
CONCLUSION: The Floor Beneath the Story
The animals have sorted themselves.
The unicorn-versus-cockroach distinction is not a classification system but a spectrum of exposure to narrative dependency. What appears to be taxonomy is actually a gradient of sensitivity to coordination.
The AI investment cycle functioned as a textbook informational cascade. Early capital was deployed on differentiated information. Later capital inferred value from prior allocation. By Q1 2026, roughly 67 percent of funding had concentrated into three mega-deals, not because uncertainty had been resolved, but because coordination had become cheaper than independent verification.
In this regime, the p-value in science and the unicorn valuation in markets perform a similar function. Both define a socially acceptable threshold at which coordination begins to substitute for judgment.
The DeepSeek shock and subsequent price competition within frontier AI disrupted this equilibrium by reintroducing commoditization precisely when valuations assumed durable scarcity. The episode exposed the central fragility of unicorn pricing: it depends not on technological impossibility, but on the continued coordination of belief around monopoly-like outcomes.
The SpaceX IPO illustrates the distinction most clearly because it contains both creatures simultaneously. Starlink’s subscriber growth, launch dominance, and operating economics resemble the cockroach. The valuation assigned to AI, orbital compute, and future optionality resembles the unicorn. The operations generate cash. The narrative generates multiples.
The distinction matters because durability and popularity are not the same thing.
Within this system, the cockroach is not low quality but low narrative dependence. TSMC’s manufacturing dominance, ASML’s EUV monopoly, and Starlink’s underlying economics continue to exist whether capital rotates toward them or away from them. Their survival function is not contingent on belief. They are not immune to markets, but they are less recursively exposed to them.
However, indifference is not immunity. The MATCH Act’s geopolitical pressure on ASML, the repricing of AI infrastructure after DeepSeek, and the historical drawdowns of mega-cap IPOs demonstrate that operational resilience and valuation resilience are distinct properties. The cockroach does not escape the system. It simply sits closer to the floor of it.
As the cascade matures, diversification itself begins to fail as a descriptive concept. Technology exposure now permeates equities, emerging markets, credit, private markets, and passive index products at once, so that growth equities, index funds, credit, and frontier private capital are no longer independent choices but different degrees of leverage to the same narrative regime. What looks like a portfolio spread across asset classes is increasingly a single trade expressed several ways. When coordination becomes the primary mechanism of price formation, diversification stops being a risk-control mechanism and becomes a visual artifact.
What remains is not a clean separation between winners and losers, but a hierarchy of responses to narrative collapse. Some unicorns eventually compress into durable cash-flow businesses once expectations reset. Others become accelerants of repricing. The determining variable is not narrative intensity. It is economic durability.
It is worth turning this lens back on the argument itself. The cockroach thesis could be the one that gets humbled. Cascades run far longer than skeptics expect, and the cost of being early is indistinguishable, for years at a time, from the cost of being wrong. Damodaran, having valued SpaceX below its offering price, still warns that it is dangerous to sell short, because a company carried by belief can stay aloft well past the point where the math stops supporting it. The investor who shorted Amazon in 1999 understood the valuation perfectly and was destroyed by the holding period. Nothing in this essay should be read as a timing signal. The claim is about which businesses survive the story leaving, not about when the story leaves, and those are different questions with different answers.
The investor’s error is to mistake attention for quality. They are not the same thing. The story attracts capital. The economics determine whether it survives after the story leaves. And in the final sorting, the market resolves not into unicorns and cockroaches, but into different degrees of sensitivity to coordinated belief.
The menu is one-dimensional.
REFERENCES
Adjemi, S., Meliani, C., and Sahnoune, H. (2026). The AI Bubble: Between Technological Promises and Economic Reality. MEST Journal, 14(1), 1-17.
Asch, S. E. (1951). Effects of group pressure upon the modification and distortion of judgment. In H. Guetzkow (ed.) Groups, Leadership and Men. Carnegie Press.
Asch, S. E. (1956). Studies of independence and conformity: A minority of one against a unanimous majority. Psychological Monographs, 70(9), 1-70.
Bell, D. E. (1982). Regret in decision making under uncertainty. Operations Research, 30(5), 961-981.
Bikhchandani, S., Hirshleifer, D., and Welch, I. (1992). A theory of fads, fashion, custom, and cultural change as informational cascades. Journal of Political Economy, 100(5), 992-1026.
Kahneman, D. and Tversky, A. (1979). Prospect theory: An analysis of decision under risk. Econometrica, 47(2), 263-292.
Kaddouhah, M. (2024). An economic definition of Fear of Missing Out (FOMO). Finance Research Letters, 63, 105344.
Kliger, D. and Kudryavtsev, A. (2008). Institutional investors, past performance, and dynamic loss aversion. Journal of Financial and Quantitative Analysis, Cambridge University Press.
Kopp, D. (2026). What Does AI Really Do to Cash Flows? An Operator’s Guide for Private Equity. Asia Tech Lens, January 27, 2026.
Kuckertz, A., Scheu, M., and Davidsson, P. (2023). Chasing mythical creatures: A (not-so-sympathetic) critique of entrepreneurship’s obsession with unicorn startups. Journal of Business Venturing Insights, 19, e00365.
Lee, A. (2013). Welcome to the Unicorn Club: Learning from Billion-Dollar Startups. TechCrunch.
Loomes, G. and Sugden, R. (1982). Regret theory: An alternative theory of rational choice under uncertainty. Economic Journal, 92(368), 805-824.
Micceri, T. (1989). The unicorn, the normal curve, and other improbable creatures. Psychological Bulletin, 105(1), 156-166.
O’Boyle, E. and Aguinis, H. (2012). The best and the rest: Revisiting the norm of normality of individual performance. Personnel Psychology, 65, 79-119.
Simonsohn, U. (2019). Syllabus, OIDD 937x: Methods Stumblers. Fall 2019.
Storm, S. (2025). The U.S. Is Betting the Economy on Scaling AI. Institute for New Economic Thinking, December 8, 2025.
The Sydenhamite (2024). Cockroach Startups. September 2024 Edition.
Verhulst, B. (2016). In defense of p values. AANA Journal, 84(5), 305-308.
Welch, I. (2000). Herding among security analysts. Journal of Financial Economics, 58, 369-396.
Primary Data Sources
Anthropic (2026). Anthropic raises $30 billion in Series G funding at $380 billion post-money valuation. Press release, February 12, 2026.
Anthropic (2026). Anthropic and Amazon expand collaboration for up to 5 gigawatts of new compute. Press release, April 20, 2026.
GetLatka (2025). Jasper AI Revenue Profile. Updated November 28, 2025. getlatka.com/companies/jasper.ai.
Jasper AI (2026). Jasper in Review: How Marketers Used Jasper in 2025. jasper.ai/blog/jasper-in-review.
Microsoft (2026). Form 10-Q, quarter ending March 31, 2026.
Morningstar (2026). SpaceX DCF Valuation $780 Billion. June 3, 2026.
PitchBook (2026). 2025 Annual US VC Valuations and Returns Report. Stanford, K., Zheng, E., and Hu, S. Published February 10, 2026.
Sacra (2026). OpenAI and Anthropic Company Profiles.
SpaceX (2026). Form S-1 Registration Statement. SEC EDGAR, filed May 20, 2026.
TSMC (2026). 1Q26 Quarterly Management Report. April 16, 2026.
The Information (2023). Jasper, an Early Generative AI Winner, Cuts Internal Valuation as Growth Slows. September 29, 2023.
Substack and Practitioner Sources
Cochrane, J. H. (2026). The Grumpy Economist. Substack Note, June 1, 2026.
Damodaran, A. (2026). To Trillion(s) and Beyond: A SpaceX IPO Odyssey! Musings on Markets, April 24, 2026.
Damodaran, A. (2026). Revisiting the SpaceX Valuation: A Post-Prospectus Update. Musings on Markets, June 5, 2026.
Damodaran, A. (2026). Valuation of SpaceX, April 2026 (pre-IPO). Spreadsheet, Musings on Markets.
Damodaran, A. (2026). Valuation of SpaceX, post-prospectus, June 2026. Spreadsheet, Musings on Markets.
Elson, E. (2026). SpaceX-stasy. Prof G Media, May 2026.
Europe Capital (2026). Current State of the AI Investment Cycle. Substack Note, February 2026.
Financial Fables (2026). AI and Tech IPOs: Force Feeding Investors. Financial Fables Substack, June 7, 2026.
Fossi, L. (2026). The SpaceX IPO Will Be the Theft of the Century. Substack, June 4, 2026.
Gupta, A. (2022). Unicorns, Gaussian Curves and Other Mythical Creatures. Psychology with Arjun, Substack, May 29, 2022.
Kuo, J. (2026). You’re About To Own Part Of SpaceX, Like It Or Not. The Big Picture, June 5, 2026.
Maandhunter, Joe (2026). Sunday Post: Week Ahead June 8-12, 2026. The M&A Hunter, June 7, 2026.
Maandhunter, Joe (2026). Profitable IPOs vs. Hype IPOs note: Why the Difference Matters. The M&A Hunter, June 8, 2026.
McBride, S. (2026). SpaceX is the new Harvard. Rational Optimist Society, April 26, 2026.
Mulberry Investment Research (2026). Megacap Tech IPOs Have Mixed Track Record. Substack Note, June 9, 2026. Citing Bloomberg and Truist.
Nikhs (2026). SpaceX and the Price of Belief. Substack Note, June 9, 2026.
Pollock, D. (2026). OpenAI’s Price War with Anthropic Could Undermine Its IPO. Yahoo Finance, June 11, 2026. Featuring analysis from Oguz Erkan (@oguzerkan), January 28, 2026.
Pithy Cyborg, Mike D. (2026). AI Just Drove Off A Cliff. Then Took Aim. And Asked For A Trillion Dollars. June 3, 2026.
QF-MI, Quantum Fields Market Intelligence (2026). Substack Note, June 2026.
Sergey (2026). What’s Really Inside SpaceX’s $1.75T IPO Valuation? Compounding Your Wealth, Substack Note, June 9, 2026.
Sirois, A. (2026). Microsoft’s $9K Return on $1K Crushes The Market. 24/7 Wall St, June 9, 2026.
The Market Dispatch (2026). Does This Mean a Crash Is Coming? A Rare and Perhaps Dangerous Chart Pattern Emerges. June 8, 2026.

Great post, thanks for mentioning me! 😊
Okay, I'm biased — I got to watch this one get built.
But the reason it works is the bit most people get wrong: you refused to let the cockroach be the hero. ASML still scars, Damodaran calls the bear case lazy, and you turn the lens back on your own thesis at the end. "Indifference is not immunity — it simply sits closer to the floor" is the whole essay in one line. Properly chuffed to have my name on it.
Thanks for letting me be the annoying one about every clean number.